One Annuities Prospectus Calculates Your Fees on an Imaginary Balance
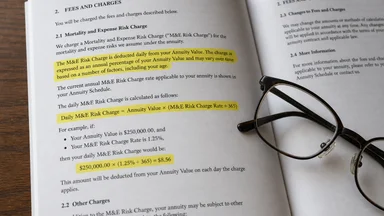
You open the prospectus for a fixed-index annuity expecting to see a simple fee. Instead, buried in a section titled “Mortality and Expense Risk Charge,” you find this: the fee is calculated on the “guaranteed minimum death benefit base” — a number that often starts higher than your premium and never declines, even when you withdraw money. Your actual account balance could be $300,000, but you're paying 1% on an imaginary $500,000. That's $5,000 a year on money you no longer have.
This is not a glitch. It is a design choice, and it is perfectly legal. The practice affects millions of retirees who own variable or fixed-index annuities, a market that held roughly $3 trillion in assets as of 2025. Yet most buyers never realize the fee base is fictional until they try to compare costs — and by then, the surrender period has locked them in.
The Imaginary Balance: A Fee Calculation You Never See
The fee basis is typically defined in the prospectus as the “guaranteed minimum death benefit base” or “income base.” These are notional values used to calculate certain guarantees — they are not the account value you see on your quarterly statement. But the insurance company uses them to compute its ongoing fees. The result is that you pay an annual charge on a principal amount that may be far larger than what you actually own.
For example, a common variable annuity might charge an annual mortality and expense risk fee of 1.25% on the death benefit base. If you invested $200,000 and the base is set at $200,000, but after withdrawals your account drops to $150,000, you still pay 1.25% on $200,000. Over a decade, that extra $50,000 in phantom principal generates roughly $6,250 in fees you would not have paid if the charge were based on actual value.
Industry representatives argue that this fee compensates the insurer for the risk of guaranteeing a minimum death benefit — a promise that costs money regardless of the account's performance. But critics note that the fee is charged every year, even when the guarantee is never triggered. The insurer collects the same revenue whether markets rise or fall, while the retiree's account shrinks.
To understand why the notional base persists, consider the mechanics of a typical contract. The death benefit base is often set equal to the initial premium at purchase. If the contract includes a “ratchet” feature that locks in market gains, the base can step up to a higher value. But when you make a withdrawal, the base may be reduced by a proportionate formula — for example, if you withdraw 10% of your account, the base drops by 10% of its current value. However, many contracts use a “dollar-for-dollar” reduction only for the first withdrawal amount, then switch to proportionate. The result is that a retiree who takes a large withdrawal early may see the base decline far less than the account. One common provision: “Partial withdrawals reduce the death benefit base by the amount withdrawn, except that if the withdrawal exceeds the accumulated earnings, the excess reduces the base dollar-for-dollar.” This language can confuse even experienced advisors.
A 2022 study by the Insured Retirement Institute found that roughly 40% of annuity owners had made a partial withdrawal in the prior five years. For those owners, the gap between the notional base and actual account value can widen significantly. The study estimated that the average gap for contracts with withdrawal activity was roughly $15,000 to $25,000, depending on contract features.
How the Fine Print Defeats the Ordinary Reader
Annuity prospectuses are notoriously dense. The average contract runs 40 to 60 pages, and the fee disclosure is often scattered across multiple sections. The Securities and Exchange Commission requires a “risk factors” section, but it does not mandate a plain-English summary of how fees are calculated. State insurance regulators, who oversee annuity sales, rarely test whether consumers understand the difference between a notional base and an actual balance.
Consider the language from a typical prospectus: “The mortality and expense risk charge is calculated daily based on the guaranteed minimum death benefit base, which is equal to the initial premium adjusted for any additional premiums and partial withdrawals in accordance with the contract’s provisions.” The phrase “in accordance with the contract’s provisions” hides the key fact: partial withdrawals reduce the base by less than the amount withdrawn, or not at all. A retiree who reads carefully might still miss the implication.
Academic studies suggest that roughly 80% of annuity buyers overestimate the liquidity of their product and underestimate the fees. In one 2023 survey by the Consumer Federation of America, fewer than one in five respondents could identify the fee basis of their own annuity. The fine print is designed for regulators, not for buyers.
Moreover, the prospectus typically does not provide a simple example of how a withdrawal affects the fee. A retiree would need to locate the “partial withdrawal” provision, cross-reference it with the “fee calculation” section, and then perform a mathematical computation. Most never do. Even financial advisors sometimes overlook the distinction. A 2024 mystery-shopper study by the National Association of Insurance Commissioners found that only about half of agents could correctly explain how fees change after a partial withdrawal.
The problem is compounded by the fact that the notional base is often referred to by multiple names in the same document: “death benefit base,” “income base,” “guaranteed minimum base.” A retiree might see one term in the fee section and a different term in the benefits section, without realizing they are the same number. This terminological inconsistency is a feature, not a bug — it makes comparison shopping nearly impossible.
The $15 Trillion Engine That Loves This Loophole
BlackRock, the world's largest asset manager, reported a record $15 trillion in assets under management in mid-2026. A growing share of that comes from annuity-related products, including the iShares deferred income annuity ETFs and institutional separate accounts. For companies like BlackRock, the notional fee base is a gift: it decouples revenue from account performance. Even when markets fall and account values drop, fee income remains stable.
Insurance companies earn a spread on the notional base that is not linked to the actual risk they bear. For a typical variable annuity, the insurer might collect an annual fee of 1.25% on a death benefit base that is $100,000 higher than the account value. That is an extra $1,250 per contract per year. With millions of contracts in force, the aggregate revenue boost runs into the billions.
There is no incentive to simplify disclosure voluntarily. The industry has fought state-level attempts to require a “total cost” illustration that shows fees in dollar terms. As of 2026, only a handful of states have adopted such rules, and they apply only to indexed annuities, not variable ones. The National Association of Insurance Commissioners has studied the issue but has not issued a model regulation.
Consider the lobbying effort: In 2023, the insurance industry spent roughly $150 million on federal lobbying, according to OpenSecrets. A significant portion targeted financial services regulation, including annuity disclosure rules. The industry's argument is that requiring a dollar-cost illustration would be “misleading” because it would require assumptions about future market performance. But the same logic would apply to mutual fund fee tables, which have been required for decades. The real objection is that transparent disclosure would reduce sales.
Meanwhile, the SEC has taken some steps. In 2022, it proposed amendments to Form N-4 that would require a standardized fee table for variable annuities, but the proposal did not address the notional base issue directly. The final rule, adopted in 2024, requires a table showing fees as a percentage of account value, but it does not mandate that the fee base equal the account value. Insurers can still use a notional base and simply report the percentage applied to that base, which may be lower than the effective percentage on the actual balance.
Follow the Money: Who Benefits from the Misunderstanding
The primary beneficiary is the insurance company. The fee-on-fictional-balance directly increases shareholder returns. For publicly traded insurers like MetLife, Prudential, and AIG, annuity fees contribute a significant portion of operating income. In 2025, MetLife reported roughly $4 billion in net investment income and fees from its retirement and income solutions segment, much of it from annuity contracts.
Brokers and agents also benefit. Commissions are typically based on the initial premium, not the account value, so they have no financial incentive to explain the fee base accurately. A broker who sells a $500,000 annuity earns the same commission whether the client later withdraws $200,000 or not. The ongoing trail commission, if any, is also tied to the account value, but the initial lump sum is what drives behavior.
Regulators have received relatively few consumer complaints specifically about notional fee bases, partly because victims rarely realize they are being overcharged. The SEC's Office of Investor Education and Advocacy has published warnings about annuity fees, but it does not track complaints by fee-calculation method. The Consumer Financial Protection Bureau could theoretically act under its authority to police unfair or deceptive acts, but it has not prioritized annuity fee disclosure.
However, there is a growing chorus of critics. The Consumer Federation of America has called on the NAIC to require that all annuity fees be calculated on the account value. In 2024, the group published a white paper estimating that the notional base practice costs retirees roughly $2 billion to $3 billion annually in excess fees. The paper also noted that the practice disproportionately harms older retirees, who are more likely to take withdrawals and less likely to understand complex disclosures.
Some state regulators are starting to act. In 2025, the California Department of Insurance issued a bulletin reminding insurers that fee disclosure must be “clear and conspicuous” and that using a notional base without clear explanation may be considered a deceptive practice. The bulletin stopped short of banning the practice, but it signaled that regulators are watching. A similar effort in New York has stalled due to industry pushback.
The Real Cost: A Retiree's Retirement Math
Let us walk through a concrete scenario. A retiree, call her Maria, invests $300,000 in a variable annuity with a guaranteed minimum death benefit base of $500,000. The contract charges a 1% annual mortality and expense fee on that base. She plans to withdraw 6% of her account value each year — roughly $18,000 initially. After the first year, her account drops to $282,000, but her fee is still $5,000 (1% of $500,000). If the fee were based on her actual balance, it would be $2,820. She pays an extra $2,180 in year one.
Over ten years, assuming a 5% annual return on the account and continued withdrawals, the extra fees compound. A conservative estimate puts the total overpayment at roughly $20,000. If that money had remained invested at 5%, it would have grown to more than $30,000. Maria effectively subsidizes the insurer's capital base for a guarantee she may never use.
This is not an edge case. Industry data suggests that a significant minority of annuity contracts have death benefit bases that exceed account values by 20% to 50%. For contracts with “ratchet” features that lock in gains, the gap can be even larger. Retirees who take partial withdrawals are especially penalized, because the notional base often declines more slowly than the account.
Consider another example: John, age 70, invests $400,000 in a fixed-index annuity with a 1.5% fee on the income base, which is set at $450,000. He takes a one-time withdrawal of $100,000 for a home repair. His account drops to $300,000, but the income base might only reduce to $400,000, depending on the contract's formula. He now pays 1.5% on $400,000 ($6,000) instead of 1.5% on $300,000 ($4,500). The extra $1,500 per year continues indefinitely, even though the guarantee may never be used. Over 15 years, that is $22,500 in excess fees. If John had known this, he might have chosen a different product or taken a smaller loan instead.
The impact is even more severe for those who annuitize. When you convert your account to a lifetime income stream, the fee calculation may shift to the income base, which can be much larger than the remaining account value. A retiree who annuitizes after years of withdrawals may find that the fee base is still near the original premium, while the actual account has been largely depleted. This can reduce the monthly income by 10% to 20% compared to a product that charges on the actual balance.
What a Transparent Prospectus Would Look Like
A truly transparent prospectus would show the fee as a dollar amount per $1,000 of actual account value, not as a percentage of a fictional base. It would include a table of cumulative fees over 5, 10, and 20 years under realistic withdrawal scenarios. It would answer the question: “If I withdraw $50,000, how much does my fee drop?” The answer should be immediate, not buried in a formula.
The United Kingdom already requires something close. Since 2018, the Financial Conduct Authority has mandated a “key facts illustration” for all retail investment products, including annuities. The illustration shows the total projected cost in pounds and pence over the life of the product, assuming a range of market returns. It also shows the impact of charges on the final value. U.S. regulators could adopt a similar standard without new legislation.
State insurance commissioners have the authority to mandate such disclosures under their existing consumer protection powers. The NAIC's Annuity Disclosure Model Regulation, last updated in 2024, requires an illustration of benefits but does not require a dollar-cost projection of fees. A simple amendment could close the gap. The SEC, which oversees variable annuities, could also update its Form N-4 to require a plain-English fee table that uses the account value as the base.
Some product manufacturers are already moving in this direction. A few fixed-index annuities now offer a “fee base” that equals the account value, marketed as a transparency feature. These products tend to have lower headline fees but may offset the difference with higher surrender charges or lower caps. The trade-off is worth examining: a transparent fee base might cost the same in total, but it allows the consumer to see the true cost and make informed comparisons. As of 2026, these products represent a small fraction of the market, but their presence shows that change is possible.
One Change That Would Close the Gap
The most straightforward fix is a rule requiring that the fee base equal the current account value minus any applicable surrender charges — nothing more. A joint proposal by the SEC and NAIC along these lines would immediately eliminate the phantom principal problem. The Consumer Financial Protection Bureau has authority under the Dodd-Frank Act to police unfair or deceptive practices in consumer financial products, and it could issue a guidance clarifying that notional fee bases are presumptively unfair.
A precedent exists in the mutual fund industry. In the 1980s, funds charged 12b-1 fees that were often hidden and poorly disclosed. After years of regulatory pressure and eventual rule changes, funds are now required to show 12b-1 fees prominently in a standardized fee table. The result was a dramatic reduction in the use of these fees for marketing, and better outcomes for investors. A similar reform for annuity fees would likely produce similar results.
Until that change happens, the best defense is a simple question. Before signing an annuity contract, ask your adviser: “What is my fee base today? Is it my current account value, or some other number?” If the answer is anything other than your actual balance, you know you are paying for imaginary money. And you have a choice: walk away, or demand a product that charges only on what you actually own.
This article is for informational purposes only and does not constitute personalized financial or legal advice. Consult a qualified professional for advice regarding your individual situation.