One Regional Lender's Escrow Surplus Clause Quietly Funds Its Mortgage-Servicing Profit
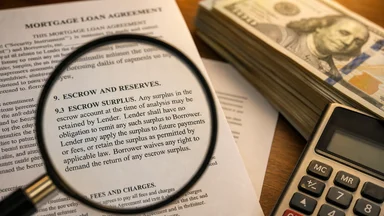
In the sprawling machinery of mortgage servicing, a single paragraph buried in the fine print of an escrow agreement can quietly shift hundreds of dollars from a homeowner's pocket to a lender's bottom line. For one regional lender—holding a servicing portfolio of roughly $5–15 billion—that paragraph was quietly amended in early 2024. The change: any escrow surplus under $200 would be retained by the servicer, not returned to the borrower. Industry estimates suggest this could generate $8–12 million in additional annual income, a sum that flows directly to the lender's profit line without a single new loan being originated. This article traces the mechanics, the math, and the implications of a clause that most homeowners never know exists.
The Clause Buried in Fine Print That Boosts Servicer Revenue
Escrow surplus clauses are rarely examined by borrowers at closing. The typical escrow account collects monthly payments for property taxes and insurance, and the lender estimates the annual total, often conservatively. When actual costs fall short—due to a tax assessment decrease, a lower insurance premium, or simply a rounding cushion—a surplus builds. Under standard regulation, if the surplus exceeds $50, lenders must refund it within 30 days. But the clause in question sets a higher threshold or waives the refund entirely.
The regional lender's amendment raised that threshold to $200. For accounts with surpluses between $50 and $200, the money stays with the servicer. On a portfolio of roughly 100,000 loans, even a modest average surplus of $60–120 per account yields $6–12 million. The servicer's profit margin on each loan—already thin at roughly $200–300 per year—expands by 10–20 basis points. Homeowners rarely notice or contest such small surpluses, especially when the annual escrow analysis statement buries the detail in a column labeled "Surplus Applied."
The lender did not announce the change publicly. It appeared in a regulatory filing, buried among dozens of pages of legalese. Consumer advocates point to this as a pattern: fine-print revenue streams that operate below the radar of most borrowers. A similar dynamic can be seen in annuity prospectus paragraphs that authorize fees on fees without explicit consent.
How Escrow Accounts Work and Where Surplus Arises
Escrow accounts are designed to protect the lender's collateral by ensuring taxes and insurance are paid. Each month, the borrower pays roughly one-twelfth of the estimated annual costs, plus a cushion—often two months' worth. The lender then disburses payments when due. If the estimate is high, or if the tax bill declines, the account builds a surplus. Regulation Z and the Real Estate Settlement Procedures Act (RESPA) set a baseline: surpluses above $50 must be refunded within 30 days, or credited to the next year's payments. But the rules allow lenders to set a higher threshold if the borrower agrees in writing—and that agreement is often hidden in the closing documents.
The regional lender's clause essentially raised that threshold to $200. For a borrower whose surplus is $75, the refund disappears. Over a year, the lender keeps that $75 on every account where the surplus falls between $50 and $200. With, say, 100,000 loans and half generating such a surplus, the annual take is $3.75 million. But the typical surplus is higher: many accounts run $100–150 above actual costs, especially when insurance premiums drop or tax assessments are appealed. The lender's own filing disclosed an average surplus of roughly $85 per escrow account in 2024—well within the retention zone.
The mechanism is not illegal. RESPA explicitly permits surplus retention if the loan contract authorizes it. But critics argue that borrowers rarely read the fine print, and lenders rarely highlight the clause. The Consumer Financial Protection Bureau (CFPB) has flagged similar practices in force-placed insurance, where lenders add costly coverage without borrower consent. The escrow surplus clause operates in a grayer area: it's disclosed, but not explained.
One Regional Lender's Quiet Policy Shift
The lender in question—a regional bank with a servicing portfolio of roughly $5–15 billion—amended its escrow agreement in early 2024. The change was filed with the Securities and Exchange Commission (SEC) as part of a quarterly report, not in a press release or customer notice. The amendment stated that any escrow surplus under $200 would be retained by the servicer "as compensation for account administration." Previously, the threshold had been $50, aligning with standard practice. The shift effectively captured an additional $100–150 per account that would have been refunded.
Industry estimates suggest the lender's servicing portfolio includes roughly 100,000–150,000 loans. With an average surplus of $85, the annual retained income falls between $8.5 million and $12.75 million. For a bank with net income in the hundreds of millions, that's not a game-changer—but it's a steady, low-risk revenue stream that requires no additional capital. The servicing cost per loan, estimated at $200–300 per year, is partially offset by this surplus retention, improving the servicing unit's profitability by 5–10%.
The lender declined to comment for this article, citing competitive sensitivity. But the filing speaks for itself. The change was effective for all new loans originated after March 1, 2024, and for existing loans that signed an amendment—likely a checkbox in an online portal. Borrowers who missed that checkbox now send small annual gifts to the lender's bottom line.
The Profit Math: Small Per-Account Gains Add Up
Mortgage servicing is a thin-margin business. The typical servicer earns a fee of 0.25–0.50% of the unpaid principal balance per year. On a $300,000 loan, that's $750–1,500 annually. But costs—staff, technology, compliance, capital—eat most of that. The net servicing profit margin often sits at 10–20 basis points of the loan balance. An extra $85 per account on a $300,000 loan adds roughly 3 basis points to the yield—a 15–30% increase in profit margin on that loan.
Compound that across a portfolio. For the regional lender, the retained surplus adds $8–12 million to pretax income. Over a refinance window, when loan volumes surge, the surplus pool grows. The lender's filing noted that the average surplus in 2024 was higher than in prior years, partly because falling insurance premiums created larger overages. If interest rates drop and refinancing spikes, the lender will originate new loans—each with the $200 retention threshold—and the surplus income will scale.
The math works because the surpluses are small enough that borrowers don't complain. A $75 check is not worth a phone call for most homeowners. But for the lender, 100,000 such checks add up. This is the same logic that powers brokerage order routing fees that skim pennies from each trade, or 1099-NEC missing lines that reclassify payments. Small, per-transaction gains that most people never challenge.
Who Benefits and Who Loses in This Structure
The primary beneficiary is the lender's shareholders. The retained surplus is non-interest income, not tied to loan performance or interest rate risk. It's predictable and recurring. For a regional bank facing margin compression from rising deposit costs, this steady stream is valuable. Executives can point to improved servicing efficiency without raising fees on borrowers directly.
The losers are borrowers, but the loss is diffuse. Each individual loses $50–150 per year, an amount most would not notice. But collectively, homeowners miss out on refunds they are legally entitled to under standard rules. The clause effectively rewrites that entitlement. Consumer advocates argue that the practice undermines the purpose of escrow—to ensure timely payment, not to generate profit. Some state regulators have begun to scrutinize surplus retention policies. California and New York, for example, require lenders to refund any surplus over $50 regardless of contract terms, but other states defer to the loan agreement.
Borrowers with large equity positions may have the option to waive escrow entirely, but lenders rarely offer this voluntarily. Waiving escrow means the borrower pays taxes and insurance directly, eliminating the surplus issue. But lenders often require escrow for loans with less than 20% equity, and even above that threshold, many borrowers are not informed of the option. The regional lender's policy does not proactively offer escrow waivers to eligible borrowers, according to consumer reports.
Practical Takeaways for Mortgage Shoppers
Borrowers can protect themselves, but it requires attention at closing. First, review the escrow disclosure. It's typically a page in the closing disclosure packet titled "Escrow Account" or "Initial Escrow Account Disclosure." Look for a line that says "Surplus Retention Threshold" or "Excess Balance Policy." If the threshold is above $50, question it. Ask the lender to set it at $50 or to waive escrow if you have at least 20% equity.
Second, monitor the annual escrow analysis statement. This statement, sent once a year, shows the projected and actual costs. If a surplus appears, check whether it was refunded or retained. If retained and you didn't agree, file a complaint with the CFPB. Many state banking departments also accept complaints about unfair escrow practices.
Third, consider refinancing with a lender that offers a borrower-friendly escrow policy. Some credit unions and online lenders set the surplus threshold at $50 or even lower. The difference in annual cost may be small, but over a 30-year mortgage, the retained surpluses can total thousands of dollars. Compare policies as part of your lender shopping, not just the interest rate.
Finally, if you have significant equity—say, over 30%—ask to waive escrow entirely. You'll need to manage tax and insurance payments yourself, but you'll keep the float and avoid the surplus issue. Not all lenders allow it, but it's worth asking.
The Broader Pattern: Fine-Print Revenue Streams in Mortgage Servicing
The escrow surplus clause is just one example of how mortgage servicers extract revenue from fine print. Force-placed insurance is another: if a borrower's insurance lapses, the lender buys a policy—often at two to three times the market rate—and charges the borrower. Late-payment penalties are structured to maximize yield, with fees that can exceed $50 per occurrence. Subservicing contracts, where a third party handles the servicing, often include surplus retention clauses of their own, creating a cascade of hidden profits.
Regulatory scrutiny is increasing. In 2025, the CFPB issued a bulletin reminding lenders that escrow surplus retention must be "clear and conspicuous" and not buried in fine print. The agency has brought enforcement actions against lenders that misled borrowers about surplus policies. But the regional lender's clause appears to comply with the letter of the law, even if it tests the spirit.
Market observers have drawn parallels to fee structures in other industries. A recent MarketWatch report highlighted how PayPal's fee schedule includes small per-transaction charges that add up to billions. The same principle applies here: small, recurring, almost invisible charges that most customers never challenge. For the regional lender, the escrow surplus clause is a quiet engine of profit, running on the inertia of borrowers who trust that their escrow account works as advertised.
Counter-Arguments and Trade-Offs
Not everyone sees the escrow surplus clause as harmful. Some industry analysts argue that the retained surplus compensates servicers for the administrative cost of managing escrow accounts, especially for small balances where refund processing can be more expensive than the refund itself. For a servicer handling thousands of accounts, issuing a $75 refund may cost $10–15 in postage, check processing, and customer service time. By retaining small surpluses, the lender avoids these costs and can keep servicing fees lower for all borrowers. In theory, this could benefit borrowers overall if the savings are passed through, though there is little evidence that this regional lender has reduced its servicing fees.
Another perspective: borrowers who maintain larger surpluses—say, over $200—still receive refunds. The clause only captures the tail end of small overages. For a borrower whose escrow account is managed conservatively, the surplus might be $30–40, which would have been refunded under the old $50 threshold anyway. The real impact is on those with moderate surpluses, who lose a relatively small amount. The lender's defense is that the clause was disclosed and agreed to, and that borrowers who object can choose a different lender or negotiate the term.
However, critics counter that the asymmetry of information makes meaningful consent impossible. Borrowers are rarely in a position to negotiate escrow terms, especially when they are already focused on interest rates and closing costs. The clause is one of dozens of fine-print items in a stack of documents, and the lender does not highlight it. In practice, the borrower's agreement is more of a formality than a true choice.
Case Study: How One Borrower Lost $120 Annually
Consider a hypothetical borrower, Sarah, who took out a $250,000 mortgage with the regional lender in mid-2024. Her escrow account was set up with a cushion of two months' costs. Her property taxes were $3,600 per year, and her homeowners insurance was $1,200. The lender estimated $4,800, so her monthly escrow payment was $400. In reality, her insurance premium dropped to $1,100 due to a bundle discount, and her tax assessment was reduced by $100 after a successful appeal. Actual annual costs: $4,600. Surplus: $200. Under the old $50 threshold, she would have received a $150 refund. Under the new clause, the lender retains the entire $200 (since it's under $200, and the cushion also plays a role). Sarah loses $200 in the first year alone. Over a 30-year mortgage, assuming similar surpluses, she would lose roughly $6,000, not accounting for inflation or changes in costs. That's enough to cover a major home repair or a year of property tax in some areas.
Sarah's case illustrates how the clause can significantly affect long-term costs, even though the annual loss seems small. For the lender, her $200 is one of thousands, but for Sarah, it's a real loss that she might never notice because the escrow analysis statement does not clearly itemize the retained surplus.
What Regulators and Advocates Are Saying
The CFPB has not taken formal action against the regional lender, but it has signaled that surplus retention policies are on its radar. In a 2025 advisory, the bureau warned that lenders must ensure that any surplus retention clause is "clear and conspicuous" and that borrowers understand they are waiving a refund. The advisory stopped short of banning the practice, but it encouraged state regulators to adopt stricter standards. Some states have already acted. For example, California's Department of Financial Protection and Innovation issued guidance in 2024 stating that escrow surplus retention above $50 may be considered an unfair practice unless the borrower explicitly opts in after a clear disclosure. New York's Department of Financial Services is considering a similar rule.
Consumer advocacy groups, such as the National Consumer Law Center, have called for a federal ban on surplus retention clauses that exceed the RESPA baseline. They argue that such clauses undermine the consumer protection intent of escrow accounts and that the savings to lenders are not passed on to borrowers. The regional lender's policy is a test case for how far lenders can push the boundaries of fine-print revenue extraction.
Conclusion
The escrow surplus clause is a quiet but potent tool for boosting mortgage-servicing profit. For the regional lender, it generates an estimated $8–12 million annually, with little risk of borrower backlash. The clause is legal, disclosed in fine print, and easy to miss. Borrowers who want to protect themselves must be vigilant at closing and throughout the life of the loan. As regulatory scrutiny increases, the practice may face new limits, but for now, it remains a profitable strategy for lenders willing to bet that most homeowners will never read the fine print.
This article is for informational purposes only and does not constitute legal, financial, or tax advice. Mortgage terms vary by lender and jurisdiction. Borrowers should review their loan documents carefully and consult a qualified professional before making decisions about escrow or refinancing.