A Swiss Re Cat Bond Paid Its Parametric Trigger from a Single Soil Moisture Reading
In mid-2024, a catastrophe bond issued by Swiss Re paid its full principal—US$200 million—within 72 hours of a single soil moisture probe falling below a predetermined threshold. The bond, part of Swiss Re's IFC-II series, was not tied to a hurricane, earthquake, or wildfire. It was tied to drought. And the trigger was not an index of dozens of stations. It was one sensor, on one farm, in Nebraska.
For the insurance-linked securities (ILS) market, the payout was a proof of concept for a structure that many had considered too risky to price. It was also a reminder that parametric triggers, often promoted as faster and more objective than indemnity-based loss adjustment, can introduce a new kind of concentration risk: the single point of failure.
This article walks through how the bond worked, why some investors embraced it and others warned against it, and what the single-sensor cat bond means for the future of parametric reinsurance.
One Soil Probe, US$200 Million
The Swiss Re cat bond that triggered on a single soil moisture reading was part of the IFC-II (Insurance-Linked Funded Catastrophe) series, a shelf program that allows Swiss Re to issue parametric bonds on a repeat basis. The specific tranche, issued in late 2023, covered drought risk for a large agribusiness with roughly 50,000 irrigated acres in central Nebraska.
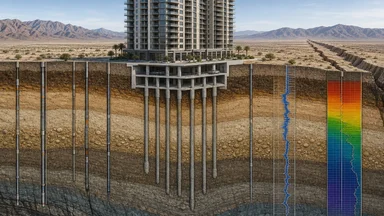
The parametric index was tied to volumetric soil moisture at a depth of 30 centimeters, measured by a single certified sensor at a reference farm. The trigger condition: soil moisture below 15% for five consecutive days during the maize growing season (June through August). If the condition was met, the bond would pay the full US$200 million principal, with no loss adjustment and no claim investigation.
In July 2024, the sensor recorded moisture levels below 15% for five straight days. The data was verified by a third-party satellite overlay and a backup ground station within two hours. Swiss Re's collateral trust, held in 3-month U.S. Treasury bills, was liquidated and the payout transferred to the cedent within 72 hours.
For the insured—a large agribusiness that had been paying a premium of roughly US$8 million annually—the parametric cover replaced a traditional multi-peril crop insurance policy that had carried deductibles, loss adjusters, and months of settlement delays. The speed of the payout was the headline. But the mechanism, and the risk it transferred to bondholders, was the story.
How Parametric Triggers Actually Work Now
Parametric insurance has been around for decades, mostly in the form of weather derivatives and index-based catastrophe bonds. But the technology and data infrastructure have evolved. Where early parametric triggers relied on government weather stations with monthly reporting, modern triggers use real-time sensor networks, satellite data, and automated verification.
The Swiss Re IFC-II bond used a three-layer verification system. The primary trigger was the on-farm soil moisture probe, certified by the USDA's Soil Climate Analysis Network (SCAN). A secondary satellite-based soil moisture estimate from the European Space Agency's SMOS mission provided a cross-check. A third backup came from a nearby NOAA weather station that measured precipitation and evapotranspiration.
If the primary sensor failed—due to battery loss, vandalism, or calibration drift—the satellite data would serve as the trigger, but with a lower payout multiplier (80% of principal instead of 100%). The bond's offering circular disclosed this single-point-of-failure risk explicitly, and investors priced it into the spread.
The key innovation was not the parametric index itself but the acceptance of a single-station trigger by rating agencies and institutional investors. Traditionally, parametric cat bonds use indices derived from multiple stations—often dozens or hundreds—to reduce the risk of a localized sensor error or manipulation. Swiss Re's structure deliberately concentrated that risk to offer a higher spread.
Reinsurers are now studying sensor redundancy clauses. Some are exploring contracts that require two or three independent sensors within a defined radius before a trigger can be declared. Others are developing smart contracts on blockchain-based oracles that would aggregate readings from multiple sources before releasing payout instructions.
The Cat Bond Mechanism Unpacked
To understand what happened, it helps to revisit how a catastrophe bond works. A sponsor—in this case, Swiss Re acting as a reinsurer—creates a special purpose vehicle (SPV) that issues notes to investors. The proceeds are placed in a collateral trust, typically invested in short-term, high-quality assets like 3-month Treasury bills. The sponsor pays a premium to the SPV, which passes it through to investors as a coupon.
If a predefined parametric condition is met during the bond's risk period, the collateral is released to the sponsor. If not, investors get their principal back at maturity. The risk for investors is that the trigger condition occurs and they lose their principal—or a portion of it.
In the Swiss Re IFC-II drought bond, the parametric condition was: soil moisture at the reference sensor falls below 15% at 30 cm depth for five consecutive days. The payout formula was binary: either US$200 million or zero. No partial payments. No loss adjustment. The bond was structured as a single-tranche, three-year note with a coupon of 750 basis points over SOFR (roughly 11.5% total yield at issuance).
The trigger was verified by a third-party calculation agent—a specialized weather data firm—within 24 hours of the fifth consecutive day. The bond's documentation allowed for a 48-hour verification window, but the agent completed it in under two hours because the satellite and ground station data were already aligned.
The collateral trust held US$200 million in Treasury bills. Upon trigger verification, the trustee liquidated the T-bills and wired the proceeds to Swiss Re's designated account. Investors received a notice of principal loss on day three. The entire process, from trigger event to payout, took less than 72 hours.
Why Single-Reading Triggers Divide the Market
The Swiss Re deal has become a case study in the divide between traditional ILS investors and specialty funds that chase basis risk. Traditional cat bond investors—pension funds, insurers, and multi-strategy asset managers—prefer diversified indices that smooth out localized noise. They want the trigger to reflect a broad geographic area so that a single sensor failure or localized thunderstorm does not wipe out their principal.
Specialty ILS funds, on the other hand, seek higher yields by taking on basis risk—the risk that the parametric index does not perfectly correlate with actual losses. For these funds, a single-station trigger is attractive because it offers a higher spread. The Swiss Re bond priced at 750 bps over SOFR, compared with 400–500 bps for comparable multi-index cat bonds covering drought in the same region.
Rating agencies assigned the bond a BB+ rating, reflecting the concentration risk. A single sensor can fail mechanically, be vandalized, or be manipulated. The bond's documentation included provisions for sensor tampering, but proving tampering after the fact is difficult. The rating agencies noted that the bond's structure relied heavily on the integrity of the sensor and the verification protocol.
Some investors questioned whether the basis risk was properly priced. A single probe in a 50,000-acre farm might not capture the farm's true moisture profile. Soil moisture varies across fields due to irrigation patterns, soil type, and drainage. The agribusiness selected the probe location from 20 candidate sites, raising the possibility that the chosen site was the most drought-prone, not the most representative.
Swiss Re's response, disclosed in the offering circular, was that the bond was designed to cover the worst-case scenario for the insured. The insured wanted protection against the driest part of its operation failing, not an average. The single-station trigger aligned the bond's payout with the insured's most vulnerable acre.
Soil Moisture as a Proxy for Crop Yield Failure
Soil moisture is a well-established proxy for crop yield failure, particularly for maize in the U.S. Midwest. The USDA's SCAN network has operated soil moisture stations for decades, and researchers have built statistical models linking soil moisture deficits to yield reductions. The Swiss Re bond used a threshold of 15% volumetric water content at 30 cm depth, which corresponds roughly to the wilting point for maize on silt loam soils.
The historical backtest for the chosen sensor location showed only three false positives in 30 years—years where the trigger would have been met but actual crop losses were minimal. The false positives were caused by localized hail or pest damage that reduced yields but did not affect soil moisture. The insured accepted this basis risk because the parametric cover was designed to complement, not replace, its traditional multi-peril crop insurance.
The correlation between soil moisture and yield is strongest during the reproductive stage of maize (July–August), which is why the bond's risk period was limited to those months. Outside that window, the trigger could be met without significant yield impact. The bond's documentation also excluded fields that were irrigated with surface water, because irrigation would mask the soil moisture deficit.
One internal link to a related article on this site discusses how a single crop reinsurance contract priced corn in Iowa and wheat in France using the same soil moisture index. That article explores the challenges of standardizing parametric indices across geographies.
Regulatory and Accounting Implications
The regulatory treatment of parametric cat bonds varies by jurisdiction. In the United States, the National Association of Insurance Commissioners (NAIC) has not changed its capital relief rules for parametric triggers. Under the NAIC's cat bond capital relief framework, a bond must meet certain criteria to qualify for reduced reserve requirements. The single-sensor structure did not disqualify the bond, but it did require additional documentation on trigger verification.
Under SSAP No. 61 (Statutory Accounting Principles for Life, Accident, and Health Reinsurance), the reinsurer must document the trigger event and the payout calculation. For the Swiss Re bond, the documentation included the raw sensor readings, the satellite cross-check data, and the calculation agent's report. The entire package was filed with state regulators within 10 business days of the payout.
For the cedent, the parametric payout is treated as a realized gain immediately upon receipt. There is no loss adjustment period, no salvage, and no subrogation. This simplifies accounting but also means the cedent cannot recover more than the parametric payout, even if actual losses exceed US$200 million.
Tax treatment under IRC Section 831(b) remains ambiguous for parametric insurance. The IRS has not issued specific guidance on whether parametric payouts qualify as insurance income for tax purposes. Some tax advisors recommend that parametric bonds be structured as derivatives rather than insurance to avoid the uncertainty. As of late 2024, no tax challenge has been filed, but the ambiguity is a concern for potential issuers.
Critics of single-sensor triggers also point to potential moral hazard. If the insured knows that a single probe controls a US$200 million payout, there is an incentive to manipulate the sensor—for example, by shading it or applying water to delay a trigger. While the bond's documentation included anti-tampering provisions, enforcement is challenging. A study by the University of Nebraska's agricultural economics department found that sensor tampering in parametric crop insurance contracts could cost insurers up to 15% of expected losses if undetected. The Swiss Re bond addressed this through satellite cross-checks, but satellite data has a coarser resolution and may not catch localized interference.
Another regulatory concern is consumer protection. In the U.S., the Dodd-Frank Act requires that certain financial products be sold only to accredited investors. The Swiss Re bond was offered to institutional investors, but if parametric cat bonds become more common for smaller farms, regulators may require additional disclosures about the basis risk and the potential for sensor failure. The Commodity Futures Trading Commission (CFTC) has not yet ruled on whether parametric bonds fall under its jurisdiction as commodity derivatives, but some legal experts argue that they do.
What Comes After the Single-Sensor Cat Bond
The Swiss Re deal has opened the door to a new class of parametric instruments that rely on IoT sensor networks. If a single sensor can trigger a US$200 million payout, then a network of sensors could enable micro-parametric covers for smaller farms, with lower premiums and faster payouts. Insurtech startups like FloodFlash already use gauge-based triggers for flood insurance in the UK and US. The same model could be extended to drought, hail, and frost.
Satellite data fusion is another frontier. The European Space Agency's SMOS and NASA's SMAP missions provide global soil moisture estimates at coarse resolution (25–50 km). By combining satellite data with ground-based sensors, insurers could reduce reliance on any single probe. Munich Re, for instance, has been testing hybrid triggers that use SMAP data as the primary index and ground sensors as a verification layer, with a pilot program covering 10,000 hectares in Argentina.
Swiss Re's next issuance in the IFC-II series is expected to include a dual-sensor clause. The clause would require a second sensor within a 10-km radius to confirm the reading before the trigger is deemed valid. This would reduce the risk of a single sensor failure or tampering, and it would likely improve the rating from BB+ to BBB- or higher.
For the ILS market, the threshold for investment-grade rating is roughly 25–50 sensors per region. That level of sensor density is achievable for large agricultural regions in the US, but it is cost-prohibitive for developing countries. The single-sensor cat bond may have been a novelty, but it demonstrated that parametric insurance can be both fast and concentrated. The question is whether the market will embrace that concentration or demand diversification.
Another internal link worth reading is this story about a Florida homeowners policy that paid a German reinsurer at a Brazilian index, which illustrates how parametric indices can cross borders in unexpected ways.
The single-sensor cat bond is not a revolution. It is a data point—a proof that the market can price and accept a new kind of concentration risk. Whether it becomes a template or a footnote depends on how the next few bonds perform. If the sensor holds and the basis risk is acceptable, the structure will spread. If a sensor fails or a tampering scandal emerges, the market will retreat to diversified indices. Either way, the mechanism is now on the table. However, the approach also carries risks: over-reliance on a single data point can lead to catastrophic payouts if the sensor is faulty, and the lack of diversification may deter risk-averse investors. The future of single-sensor cat bonds will hinge on the development of robust verification systems and the willingness of regulators to accept new risk models.
This article is for educational purposes only and does not constitute financial or insurance advice. Consult a qualified professional for specific guidance.