One Tax Deduction Form Section That Classifies Freelance Software as Inventory
Every year, thousands of freelance software developers file Schedule C and check the box that says their business is a service. It feels natural: you write code, you deliver it, you get paid. But tax law does not always follow what feels natural. Under certain circumstances, the IRS considers freelance software — even custom code written for a single client — to be inventory. And that one classification shift can turn a straightforward deduction into a multi-year capitalization headache.
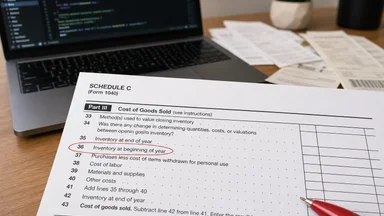
The trap is hidden in plain sight on Schedule C, Line 36, a field most freelancers leave blank. Filling it out incorrectly — or skipping it when you should not — can trigger penalties, back taxes, and interest. Worse, the rules are ambiguous enough that even experienced CPAs disagree. This article walks through the specific form line, the legal reasoning behind it, and what you can do to stay on the right side of the IRS without overpaying.
The Misclassification Trap: Why Your Freelance Software Is Not a Service
Tax law draws a sharp line between income from services and income from selling goods. Service income is straightforward: you report earnings, deduct expenses, and pay tax on the difference. Inventory income, by contrast, requires you to track cost of goods sold, capitalize certain expenses, and defer deductions until the product is sold. The distinction matters because the IRS has long held that software is tangible property for tax purposes, even though it lacks physical form.
This position dates back to Revenue Ruling 71-177 and has been reinforced in subsequent guidance. The logic: software is a product that is created, stored, and transferred, much like a physical good. When a freelancer writes code for a client, the IRS may view the transaction not as a service but as the sale of a product. The key factor is whether the developer retains ownership of the code until delivery, or whether the code is custom-built to the client's specifications and the client owns it from the start.
Many freelancers operate under a hybrid model: they build a tool, license it to multiple clients, and charge a fee. That structure looks much more like inventory than a service. The IRS has won cases against developers who treated such income as service revenue, arguing that the software was held for sale and thus subject to inventory accounting. The consequences can be severe, as we will see.
One Tax Form Line That Costs Freelancers Thousands
Schedule C, Line 36, asks: “Inventory at beginning of year.” Most freelancers skip it. But if the IRS later determines that your software was inventory, leaving that line blank means you understated your income and overstated your deductions. The result is a tax bill plus penalties and interest. The IRS can go back three years — or six if they suspect substantial understatement.
The problem is compounded by the fact that many freelancers deduct development costs — hosting fees, contractor payments, software licenses — as current expenses. Under inventory accounting, those costs must be capitalized into the cost of goods sold and deducted only when the software is sold. For a developer who builds a product over a year and sells licenses over three years, the deduction delay can be significant.
Consider an indie developer who spends $50,000 building a SaaS application in year one. If classified as a service, those costs are deductible immediately. If classified as inventory, only a portion is deductible in year one, based on units sold. The rest is deferred. For a developer with thin margins, that deferral can mean owing tax they did not expect.
The IRS provides a safe harbor for small businesses with average annual gross receipts of $26 million or less, allowing them to use simpler accounting methods. But even then, the classification of inventory is not optional: if you have inventory, you must account for it. Leaving Line 36 blank is a red flag that invites audit.
The Case of the Indie Developer Who Deducted Wrong
John is a solo developer who built a project management tool and sells it as a subscription. In his first year, he spent $45,000 on development — his own time, contractor help, and cloud infrastructure. He filed Schedule C, checked “service,” and deducted the full $45,000 as a business expense. His tax bill was zero. He felt good.
Two years later, the IRS audited him. The agent argued that John’s software was inventory because it was held for sale to multiple customers. Under Section 263A of the Internal Revenue Code, the costs of producing inventory must be capitalized. John’s $45,000 in development costs should have been added to the cost of goods sold, with only a fraction deducted each year as he sold subscriptions. The result: John owed roughly $12,000 in back taxes, penalties, and interest.
John’s story is not unusual. The IRS has pursued similar adjustments against freelancers who sell digital products. The key lesson: the nature of your income depends on how you structure your business, not just what you call it. A SaaS subscription can be inventory. A one-time custom build may be a service. The line is blurry, and the IRS tends to err on the side of inventory when the product is sold repeatedly.
John could have avoided the trap by consulting a CPA early, documenting his intent, and possibly structuring his business as a separate entity for product sales. But he did not, and he paid the price.
Capitalization Rules: What Must Be Included in Cost of Goods Sold
Under Section 263A, uniform capitalization rules apply to producers of inventory. For software, that means you must capitalize direct costs — such as developer salaries, contractor payments, and hosting fees directly tied to production — and a portion of indirect costs, including rent, utilities, and administrative expenses. The goal is to match the cost of producing the software with the revenue it generates.
For freelancers, this can be a nightmare. Indirect cost allocation requires a reasonable formula, such as square footage or hours worked. If you work from home, you may need to apportion a percentage of your rent and utilities to production. The IRS does not require perfection, but it does require a consistent method. Many freelancers simply guess, which invites scrutiny.
Hosting fees are a gray area. The IRS has not issued clear guidance on whether cloud infrastructure costs are direct or indirect. Some tax professionals argue that hosting is a period cost, deductible immediately. Others say it is part of production. The safest approach is to treat ongoing hosting as a cost of goods sold if it directly supports the delivery of the software, but to consult a CPA for your specific situation.
The IRS provides a small business exception: if your average annual gross receipts for the prior three years are $26 million or less, you are exempt from Section 263A. But that exemption does not change the inventory classification itself. You still need to account for inventory; you just get to use simpler methods. Many freelancers qualify, but they still must fill out Line 36 correctly.
How the IRS Defines Inventory for Digital Products
The IRS defines inventory as “tangible personal property” held for sale in the ordinary course of business. For years, taxpayers argued that software is intangible and thus not inventory. The IRS has consistently rejected that argument, citing case law such as Xerox Corp. v. United States and Revenue Ruling 71-177. Software is treated as tangible because it is stored on a physical medium or delivered electronically in a fixed form.
This reasoning extends to downloaded software, SaaS, and even code delivered via API. The key is not the medium but the fact that the software is a product that is sold to customers. If you develop software for a single client who owns the code, it may be a service. But if you retain ownership and license it, it is likely inventory.
Freelancers who are dealers — those who buy and sell software — may also be subject to Section 475, which requires mark-to-market accounting. But that is rare for solo developers. The more common issue is uniform capitalization, which applies to producers. The IRS has not issued a safe harbor specifically for freelancers, leaving them to interpret ambiguous rules.
The lack of clear guidance is a recurring theme. As of mid-2026, the IRS has not updated its software-specific guidance in years. Freelancers are left to rely on general principles and court cases, which often favor the IRS. The burden of proof is on the taxpayer to show that their classification is correct.
Trade-Offs in Classification: Services vs. Products
Choosing between service and product classification is not just a tax decision; it affects your entire business model. If you classify as a service, you can deduct expenses immediately and avoid capitalization complexity. But you may also limit your ability to scale, because each client requires custom work. If you classify as a product, you can sell the same software to many customers, but you must defer deductions and maintain inventory records.
Consider two developers: Maria and David. Maria builds custom websites for local businesses, each one unique. She bills by the hour, and the client owns the code. She should classify as a service, deducting her laptop, internet, and software subscriptions each year. David, on the other hand, creates a WordPress plugin and sells it on a marketplace. He has hundreds of customers. He should classify as inventory, capitalizing development costs and deducting them as licenses are sold. If David treats his plugin as a service, he risks an audit and back taxes.
But there are gray areas. What if Maria builds a custom site using a template she developed? Does the template count as inventory? The IRS might say yes, because the template is held for sale (even if used in services). To be safe, Maria should separate her template development from her custom work, perhaps in a different legal entity. Similarly, David might offer custom modifications for a fee — those modifications could be services, not product sales. Mixing the two requires careful allocation.
Another trade-off: the cost of compliance. Product classification forces you to track inventory, allocate overhead, and potentially file Form 1125-A (Cost of Goods Sold). For a solo developer, this adds hours of work each year. Service classification is simpler, but if the IRS disagrees, the penalties can be severe. The choice is between a small ongoing burden and a large potential liability.
Some developers choose to classify as a service even when they sell products, betting that the IRS will not audit them. That is a risky gamble. Audit rates for sole proprietors with high deductions are not trivial, and the IRS has been increasing enforcement in the gig economy. The safer path is to classify correctly from the start.
Practical Steps to Avoid the Inventory Trap
The simplest way to avoid the inventory trap is to structure your freelance work as a service, not a product. That means writing custom code for each client, transferring ownership, and billing by the hour or project. If you sell the same software to multiple clients, you are likely in inventory territory, and you should account for it accordingly.
If you do sell a product, consider forming a separate legal entity — such as an LLC or S-corp — for the product sales, and keep your service work in a different entity. This can help clarify the nature of each income stream and simplify accounting. It also provides liability protection, which is valuable for any developer.
When in doubt, treat development costs as capitalized and deduct them over time. This conservative approach avoids audit risk and matches the economic reality of the product. If you later determine that the costs were deductible, you can amend your return. But the reverse — deducting now and capitalizing later — is much harder to fix.
Finally, document your classification rationale. Write a memo explaining why you believe your software is a service or a product, based on your business model and the IRS guidance. This documentation can be invaluable if the IRS questions your return. And always consult a CPA who has experience with software taxation — not all tax professionals understand the nuances.
The Bigger Picture: Tax Law Lags Behind Digital Economy
The tax code was written for a world of physical goods. Software, as a digital product, does not fit neatly into categories designed for widgets and machinery. The IRS has made incremental updates, but the core framework — inventory, capitalization, cost of goods sold — remains rooted in the 1990s, when software was still distributed on floppy disks.
This lag creates uncertainty for freelancers and small businesses. The Federal Reserve's minutes from June 2026 noted persistent inflation pressures, which further complicate financial planning for independent workers. Meanwhile, the Bank of England's recent appointment of a new Chief Cashier, Rhys Phillips, signals continuity in monetary policy but does nothing to address the tax code's digital blind spots.
For now, freelancers must navigate a patchwork of rulings and case law. The burden falls on individual developers to understand the rules, or to hire someone who does. As the digital economy grows, the mismatch between tax law and reality will only widen, increasing the risk for those who treat their software as a service without careful thought.
The irony is that many freelancers are trying to comply but are tripped up by a single form line. Schedule C, Line 36, is small, but it carries outsized consequences. Understanding it — and the inventory classification it implies — can save thousands of dollars and years of stress. The tax code may not keep up with technology, but your tax return can still be correct.
This article is for informational purposes only and does not constitute professional tax advice. Consult a qualified CPA or tax attorney for guidance specific to your situation.