One Annuity Surrender Charge Exceeds the Account Value It Calculates From
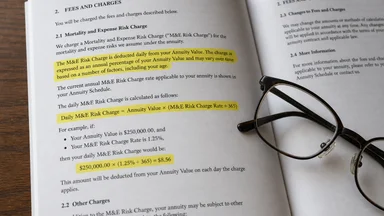
You open your quarterly annuity statement and the number is smaller than you expected. The market had a rough quarter, and your account value dropped by 15%. You decide to move the money somewhere else. Then you read the surrender charge schedule: 8% of the account value at the time of withdrawal. That 8% is applied to the pre-drop balance, or to the current balance? The contract says the charge is calculated from the account value on the date of the surrender request. If the account was $100,000 before the drop and is now $85,000, the 8% charge on the $85,000 is $6,800. But some contracts use the higher of the current value or your original investment. In that case, the fee is based on $100,000, so $8,000. Your net proceeds: $77,000. You lost $23,000 on a $15,000 market decline. That is the surrender charge trap, and it is entirely legal.
The Contract That Charges You for Paying Yourself
A deferred annuity is a contract between you and an insurance company. You pay a lump sum or a series of premiums, and the insurer invests the money, typically in bonds or a fixed-interest account. In exchange for tax deferral and a promised stream of income later, you agree to keep the money locked up for a set period—usually six to ten years. If you withdraw early, the insurer imposes a surrender charge. That charge is not a flat fee; it is a percentage of the amount withdrawn, and in many contracts, the percentage applies to the entire account value, not just the portion you are taking out.
Consider a specific example using a real product. The Fidelity Personal Retirement Annuity (FPRA) has a surrender charge schedule that starts at 8% in year one and declines by 1% each year to 0% after year eight. Suppose you invest $100,000 in this annuity. In year two, your account grows to $110,000, then the market drops 20%, leaving you with $88,000. If you decide to surrender, the charge is 7% of the current account value: $6,160. Your net proceeds: $81,840. But if the contract calculated the charge on the original investment, the fee would be $7,000, leaving you with $81,000. The difference of $840 might seem small, but in a larger account or a steeper drop, the gap widens dramatically. Now imagine the same $100,000 investment in a contract that calculates the surrender charge on the highest anniversary value. If the account reached $115,000 in year one and then dropped to $80,000 in year two, the charge might be based on $115,000, resulting in a fee of $8,050 (7% of $115,000), leaving you with $71,950. This is not a hypothetical edge case; it is how the formula works.
The surrender charge applies to the total account value, including your original principal. If you put in $100,000 and the account never grew, you could still lose $7,000 of your principal if you withdraw early. The insurer is not punishing your gains; it is punishing your exit. The logic is that the insurer front-loaded commissions and administrative costs, and the surrender charge recoups those costs if you leave before the insurer has earned them back through spreads and fees. Some contracts permit a free withdrawal of 10% of the account value per year without a surrender charge. But that free amount is calculated on the current account value, and any withdrawal above that triggers the full percentage on the entire amount. If your account drops in value, the free 10% shrinks too. And if you take the free withdrawal, you still reduce the guaranteed income base for any rider you may have purchased. The trade-off is rarely explained at the point of sale.
How the Charge Can Exceed the Account Value
The scenario that turns a bad deal into a nightmare is a market downturn combined with a surrender charge calculated on the original investment or a high-water mark. Some contracts contain a “market-value adjustment” (MVA) clause that can increase the surrender charge when interest rates rise. If the insurer’s underlying bonds lose value because rates have climbed, the MVA reduces your account further. The surrender charge then applies to the reduced amount, but the combined effect can leave you with less than half of your original investment.
In extreme cases, the surrender charge itself can exceed the remaining account value. Imagine an account that started at $100,000, fell to $30,000 due to poor investment performance and fees, and carries a 10% surrender charge on the original $100,000. The charge would be $10,000, but the account is only worth $30,000. The insurer will not let you withdraw a negative amount; they simply take the $30,000 and you get nothing. The contract may even state that if the surrender charge exceeds the account value, the insurer has no obligation to pay you anything. You have effectively lost everything.
A 2019 study by the U.S. Government Accountability Office (GAO) examined variable annuity features and noted that some contracts allow the surrender charge to be calculated on the “highest anniversary value” or the “total purchase payments,” which can be far above the current account value. The GAO report warned that this structure creates a risk of “negative surrender value,” where the fee consumes the entire account. The report did not estimate how many contracts contain such clauses, but it flagged the practice as a potential consumer protection concern.
The risk is not hypothetical. During the 2008 financial crisis, many variable annuity holders saw their account values drop by 30% or more. Those who tried to surrender faced charges based on pre-crash values, leaving them with pennies on the dollar. Some class-action lawsuits followed, but courts generally upheld the contract language. The lesson: the surrender charge schedule is not a mere administrative fee; it is a potential wealth destroyer in a downturn.
Consider a case study: In 2008, a retiree named John had a variable annuity with a $200,000 account value, which had grown from a $150,000 investment. The annuity had a 7% surrender charge in year five, calculated on the original investment. When the market crashed, his account dropped to $120,000. He needed cash for medical expenses and decided to surrender. The surrender charge was 7% of $150,000 = $10,500. After that, he received $109,500. But then the market-value adjustment clause kicked in because interest rates had risen; the MVA reduced his account by another $8,000. His net proceeds were $101,500. He lost $98,500 on a $80,000 market decline. The combination of the surrender charge and MVA turned a bad situation into a devastating one.
Why Advisors Love Selling What You Can't Leave
Annuities carry high commissions—often 5% to 10% of the premium for the selling agent. That is a powerful incentive. A $100,000 annuity sale can generate a $7,000 commission for the advisor, compared to perhaps $1,000 for a mutual fund. The surrender period ensures that the advisor does not have to worry about the client leaving and the commission being clawed back. The longer the surrender period, the higher the commission typically is.
Beyond the upfront commission, many annuity contracts pay trailing commissions of 0.25% to 1% annually for as long as the client stays in the contract. The surrender period locks in that revenue stream. An advisor who recommends an annuity with a seven-year surrender period can count on seven years of trailing fees, regardless of whether the product performs well. This is a business model, not a fiduciary recommendation.
The guaranteed lifetime income rider is the hook. It promises a steady paycheck for life, which appeals to retirees worried about outliving their savings. But the rider adds cost—often 0.5% to 1% of the account value annually—and it usually comes with its own lock-up period. If you buy the rider, you may not be able to cancel it without surrendering the entire contract. The rider masks the liquidity cost because the advisor frames it as “insurance” rather than a fee.
The Financial Industry Regulatory Authority (FINRA) has issued multiple investor alerts about unsuitable annuity sales. In a 2021 alert, FINRA warned that “annuities can be complex and may include features that are not right for everyone.” The alert specifically mentioned surrender charges and urged consumers to ask about the surrender schedule before buying. Despite these warnings, annuity sales continue to grow, driven by an aging population and aggressive sales tactics.
Another reason advisors push annuities: the products are often proprietary, meaning the advisor's firm earns additional revenue from the insurance company. This creates a conflict of interest that is not always disclosed. A 2020 study by the National Association of Insurance Commissioners found that advisors who sell annuities are more likely to recommend them to clients who are not fully aware of the surrender charges and other costs. The study recommended that regulators require clearer disclosure of surrender charge mechanics.
The Tax Treatment That Compounds the Pain
If the surrender charge were tax-deductible, the sting might be lessened. It is not. The Internal Revenue Code treats a surrender charge as a nondeductible personal expense. You pay the fee with after-tax dollars, and you receive no offset on your tax return. Furthermore, the withdrawal itself is taxed under the “last-in, first-out” (LIFO) rule: gains are deemed to come out first. So if you have $20,000 of gains in a $100,000 account, the first $20,000 you withdraw is taxed as ordinary income, even if you are taking out principal plus gains.
On top of that, if you are under age 59½, the withdrawal is subject to a 10% early-distribution penalty under IRC § 72(q). That penalty applies to the taxable portion of the withdrawal. So if you withdraw $10,000, of which $8,000 is gain, you owe $800 in penalty plus ordinary income tax on the $8,000. The surrender charge, say $7,000, is added to the loss. Your net from a $10,000 withdrawal might be less than $2,000 after fees, taxes, and penalties.
Another tax trap: annuities do not receive a step-up in basis at death. If you hold stocks or mutual funds, your heirs get a stepped-up basis equal to the date-of-death value, wiping out the capital gains tax. With an annuity, the gains are taxed as ordinary income to the beneficiary when withdrawn. The surrender charge may also apply if the beneficiary cashes out immediately, though many contracts waive the charge upon death. But the tax liability remains.
The combination of ordinary income rates (which can be as high as 37% federally, plus state tax) and the lack of a step-up means that the tax deferral benefit of an annuity is often overstated. For investors in lower tax brackets, the deferral may be worthwhile, but for high-income retirees, the eventual tax bill can be a shock.
Consider a couple in the 24% federal tax bracket. They have a $200,000 variable annuity with $50,000 in gains. If they surrender in a lump sum, the $50,000 gain is taxed at 24%, costing $12,000. If they had instead held a diversified stock portfolio, the gains might be taxed at the lower capital gains rate of 15%, costing $7,500. And if they held the stocks until death, the step-up would eliminate the tax entirely. The annuity's tax deferral is not free; it comes at the cost of higher eventual tax rates and lost step-up.
Better Ways to Defer Income Without a Cage
A simpler approach: max out your 401(k) and IRA before considering an annuity. These accounts offer tax deferral without surrender charges. You can withdraw at any time (subject to the 10% penalty before 59½) and you pay taxes only on the amount withdrawn, not on the entire account value. The fees are typically much lower—a low-cost index fund in a 401(k) might have an expense ratio of 0.03%, compared to an annuity's total annual fees of 2% to 3%.
For tax-free growth, a Roth IRA is hard to beat. Qualified withdrawals are tax-free, and there is no required minimum distribution (RMD) for the original owner. You can contribute up to $6,500 per year (as of 2023, with catch-up for those 50 and older). The trade-off is that contributions are not deductible, but for many investors, the tax-free compounding outweighs the upfront deduction.
For tax-exempt income in retirement, municipal bonds offer interest that is free from federal income tax and often state tax. A laddered bond portfolio—buying bonds that mature in successive years—provides predictable cash flow and full access to principal at maturity. No surrender charges, no market-value adjustments. The yield may be lower than an annuity's advertised rate, but the liquidity is real.
A 2020 Vanguard study estimated that the average variable annuity fee (including mortality and expense charges, administrative fees, and underlying fund expenses) reduces annual returns by about 2%. Over 20 years, that 2% drag compounds to a 33% reduction in ending account value. A low-cost index fund portfolio with a 0.1% fee would leave the investor with significantly more wealth. The study concluded that annuities are rarely the most efficient vehicle for long-term accumulation.
Another alternative is a taxable brokerage account with tax-efficient investments, such as index ETFs or municipal bonds. While you pay taxes on dividends and capital gains each year, the tax rates are often lower than ordinary income rates. And you have full liquidity—no surrender charges, no penalties for early withdrawal. For investors who prioritize flexibility, this is often a better choice than an annuity.
Reading the Fee Table Before You Sign
Every annuity contract includes a surrender charge schedule. Look for a table that lists the surrender charge percentage for each year of the contract. It should say something like: “Year 1: 8%, Year 2: 7%, … Year 8: 0%.” If the table is missing or the agent cannot produce it, walk away. Ask whether the charge applies to the amount withdrawn, the account value, or the original investment. Get it in writing.
Check for a market-value adjustment (MVA) clause. If interest rates rise, the MVA can reduce your account value on top of the surrender charge. Some contracts allow the MVA to increase the surrender charge, but never decrease it below zero. The MVA is typically found in the “adjustments” section of the contract. If you do not understand how it works, ask for a hypothetical illustration showing a 1% and 2% interest rate increase.
Compare the contract's fee table with the SEC-required prospectus fee table for variable annuities. The prospectus must show the total annual fees as a percentage of account value. Look for the “annual expenses” line. If the total is above 2.5%, you are paying a lot. Some annuities have total fees above 4% when rider charges are included. That is a heavy anchor on performance.
Ask the agent for a hypothetical withdrawal illustration. Request a scenario where the account drops 20% in year two and you need to take out $20,000. The illustration should show the surrender charge, the MVA (if any), the tax impact, and the net proceeds. If the agent cannot or will not provide it, that is a red flag. You have the right to know what you are buying.
When an Annuity Actually Makes Sense
Despite the drawbacks, annuities have a place for specific situations. A fixed immediate annuity (SPIA) converts a lump sum into a guaranteed income stream for life, with no surrender period. You give up the principal, but you get a predictable check every month. For retirees who have no heirs and worry about outliving their savings, an SPIA can provide peace of mind. The trade-off is inflation risk; the fixed payment loses purchasing power over time.
A deferred income annuity (sometimes called longevity insurance) starts payments at a future age, such as 80 or 85. The premium is relatively low because the payout is far in the future, and there is no surrender period because you cannot withdraw early. This product is suitable for someone who has sufficient assets to cover expenses until age 80 and wants a backup against extreme longevity. The cost is the loss of liquidity and the risk of dying before payments begin.
Structured settlements from lawsuits often use annuities because the payments are tailored to the plaintiff's needs and are tax-free under IRC § 104. In that context, the surrender charge is irrelevant because the plaintiff does not have the option to cash out. The annuity is simply a funding mechanism.
For most investors, an annuity should be considered only after you have maxed out your 401(k) and IRA, have a fully funded emergency fund, and have a specific need for guaranteed income that other products cannot meet. Even then, shop for a low-cost product with a short surrender period—or no surrender period at all. The insurance industry has created thousands of annuity variations, and the differences matter.
The surrender charge trap is real, but it is avoidable if you understand the mechanics before you sign. Read the contract, ask hard questions, and never buy an annuity based on a promise of tax deferral alone. The tax code offers many ways to save for retirement without locking your money in a cage with a fee that can exceed your account value. Your financial future deserves better than a product designed to penalize you for leaving.