Three Mutuals Priced Directors Liability on the Same Public Company Board at Different Risk Loads
In early 2025, a mid-sized manufacturer based in the Midwest approached three mutual insurance carriers to quote directors and officers (D&O) liability coverage for its board of directors. The company had a clean loss record, stable financials, and no pending litigation. Yet the three quotes landed at markedly different levels: the lowest came in at roughly $180,000 for a $5 million limit, the middle quote near $220,000, and the highest at about $250,000. No single loss history or exposure metric explained the gap. The dispersion — roughly 30% to 40% — reflected something deeper: the underwriting philosophy and structural constraints of each mutual.
Three Mutuals, One Board, Three Different Prices
The manufacturer's risk manager, working with a wholesale broker, submitted a uniform submission package to three mutuals that specialize in D&O for mid-market public companies. All three received the same financial statements, board biographies, industry classification (industrial machinery), and a summary of corporate governance practices. The company had no securities class actions or derivative suits in its past, and its directors had not faced any regulatory proceedings.
Mutual A, a large regional writer with a conservative reputation, returned a premium of roughly $180,000. Its underwriter cited the company's low debt-to-equity ratio and a board that included two independent directors with prior CFO experience. Mutual B, a midsized carrier known for aggressive growth in commercial lines, quoted $220,000. Its pricing model placed more weight on the company's revenue volatility and a recent product recall that had not resulted in litigation but had generated negative press. Mutual C, a smaller mutual with a niche focus on industrial risks, priced the coverage at $250,000, pointing to the board's lack of cyber expertise and a general concern about supply-chain litigation in the sector.
The risk manager asked each carrier for a breakdown of the risk load components, but only Mutual A provided a detailed file summary. The other two cited proprietary models. The broker later told the risk manager that such dispersion was common in the mutual market for D&O, where carriers lack the stock-price discipline that drives uniformity among publicly traded insurers.
Why Mutuals Price D&O Differently on the Same Exposure
Mutual insurers are owned by policyholders, not shareholders. This governance structure frees them from quarterly earnings pressure but also removes a market mechanism that tends to compress pricing differences among stock insurers. Without analysts and investors demanding consistent underwriting margins, mutuals can sustain wider pricing ranges for identical risks.
Surplus levels play a role. Mutual A, with a surplus-to-premium ratio well above industry benchmarks, could afford to write the risk at a lower load because it had ample capital to absorb unexpected losses. Mutual C, operating closer to its regulatory minimum surplus, had to charge a higher premium to protect its solvency margin. Mutual B fell in between, balancing growth targets against capital constraints.
Actuarial models also diverge. Mutual A uses a conservative model that assumes a low frequency of D&O claims for industrial companies, based on long-term industry data. Mutual C's model incorporates a higher baseline frequency, reflecting the carrier's experience with a different policyholder mix. Mutual B outsourced its pricing to a wholesale broker whose model blended public data with judgmental adjustments. Each model produced a different risk load, and none could be proven wrong until claims emerge years later.
The Role of Reinsurance in Creating Pricing Divergence
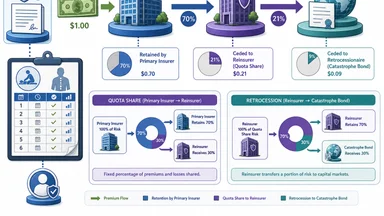
Reinsurance treaties amplify pricing differences among mutuals. Mutual A purchases a quota-share treaty that cedes 50% of its D&O exposure to a panel of European reinsurers, including Hannover Re, which recently secured a 60% upsized $200 million retrocessional cat bond (3264 Re 2026-1). The low cost of that retrocession — priced below initial guidance, according to Artemis.bm — allowed Mutual A to retain less net risk and pass some savings to the policyholder.
Mutual B uses an aggregate excess-of-loss treaty that attaches at a relatively high threshold. Because the manufacturer's D&O exposure fell below that attachment point, Mutual B bore the full risk net. Its reinsurance costs were fixed, so it could not reduce the premium to match Mutual A. Mutual C, in contrast, relies on a facultative reinsurance placement for each D&O policy above $3 million. The facultative market had hardened in 2024 and 2025, following a string of large securities class-action settlements. The carrier passed that higher cost to the buyer.
The reinsurance market's hardening after large losses in 2023-2025 affected each mutual differently depending on its treaty structure and panel of reinsurers. Mutual A's long-term relationship with Hannover Re and other European reinsurers gave it access to stable pricing. Mutual C, with a smaller panel, faced higher ceded premiums. The divergence illustrates how reinsurance architecture — not just underwriting judgment — creates pricing gaps in the mutual sector.
How Underwriting Philosophy Beats Actuarial Precision
Actuarial models provide a starting point, but each mutual's underwriting philosophy ultimately drove the final quote. Mutual A's underwriting team had recently completed a training session on D&O risk factors for industrial firms. They placed heavy weight on the board's industry sector, noting that food and beverage companies — a sector the manufacturer was not in — faced rising litigation risks, as highlighted in WTW's Global Food, Beverage & Agriculture Risk Report 2026. Because the manufacturer was in industrial machinery, the team viewed it as lower risk and reduced the load.
Mutual B's underwriter focused on the company's financial ratios and ignored sector-specific trends. The team's philosophy held that financial strength was the best predictor of D&O loss, regardless of industry. That belief led them to a middle-of-the-road quote, neither as low as Mutual A's nor as high as Mutual C's.
Mutual C's underwriter, by contrast, had a background in cyber risk and insisted on adjusting the load upward because the board lacked a director with cybersecurity expertise. The carrier's internal guidelines required a surcharge for any public company board without a designated cyber expert, a rule that Mutual A and B did not apply. The underwriter also conducted a management interview and came away concerned about the CEO's aggressive growth strategy, which she viewed as increasing litigation exposure. That soft factor added roughly 10% to the final premium.
The three outcomes show that D&O pricing is as much art as science. Actuarial precision gives way to human judgment, and that judgment varies widely across mutuals.
Trade-Offs: Lower Premium vs. Coverage Breadth
Risk managers often assume that a lower premium means a better deal, but that is not always the case. Mutual A's policy, while cheapest, included a narrower definition of "claim" that excluded pre-suit demands — a feature that could leave the board exposed if a dispute escalates without formal litigation. Mutual B's policy offered broader entity coverage, including securities claims brought by shareholders, but at a higher price. Mutual C's policy included a cyber incident response rider, reflecting the underwriter's concern about the board's lack of cyber expertise.
The risk manager for the manufacturer had to weigh these trade-offs carefully. A cheaper policy with exclusions might save money in the short term but could prove costly if a claim arises. Conversely, a more expensive policy with broader terms might be unnecessary for a company with a clean record and stable governance. The broker recommended Mutual B as a compromise, citing its balanced coverage and moderate premium, but the risk manager ultimately chose Mutual A after negotiating a small reduction in the deductible.
This trade-off is common in D&O placements. Buyers must decide whether to prioritize price or protection, and the decision often depends on the board's risk appetite and the company's specific exposures. A board that is risk-averse may prefer a higher premium for broader coverage, while a cost-conscious board may opt for the lowest quote and accept narrower terms.
Counter-Argument: Is Pricing Dispersion Really a Problem?
Some industry observers argue that pricing dispersion in the mutual sector is not a flaw but a feature. Mutuals are designed to serve their members, not to maximize profits, and different mutuals have different risk tolerances and membership profiles. A manufacturer that values low premiums may find a natural home with a mutual like Mutual A, while a company with higher risk factors may be better served by a mutual that charges more but offers greater financial stability.
Moreover, dispersion encourages competition. If all mutuals priced the same risk identically, there would be little incentive for risk managers to shop around, and mutuals would have no reason to innovate in underwriting or service. The current system allows buyers to select the carrier that best aligns with their risk profile and budget, much like consumers choose among different insurers for auto or home coverage.
However, critics counter that the opacity of mutual pricing makes it difficult for risk managers to make informed decisions. Without standardized disclosures, buyers cannot easily compare quotes on an apples-to-apples basis. This information asymmetry benefits brokers and carriers at the expense of the policyholder. The debate between transparency and autonomy is likely to continue as the market evolves.
The Case for a Standardized D&O Risk Score
The pricing dispersion observed in this case is not unusual, but it creates inefficiencies. Risk managers cannot easily compare quotes across carriers without understanding each mutual's underwriting framework. Brokers can arbitrage the gaps by steering clients to the lowest-priced mutual, but that practice may not produce the best coverage fit. A standardized D&O risk score — similar to the Uniform Mortgage-Backed Security in the housing market — could bring transparency to the process.
Some industry observers have called for a common risk-scoring model that mutuals would use to quote D&O coverage. The model would incorporate financial ratios, industry classification, governance metrics, cyber maturity, and litigation history, producing a single score that carriers could adjust only for reinsurance costs and capital constraints. The idea has gained traction among large brokers, who see it as a way to reduce the time spent reconciling disparate quotes.
But mutuals resist standardization. Their governance structures prize local underwriting autonomy, and many view their proprietary models as a competitive advantage. A mutual's board of directors — itself composed of policyholders — may see a standardized score as a threat to the carrier's identity. Regulators have shown interest in commercial lines pricing uniformity, but the mutual sector has lobbied against it, arguing that flexibility allows them to serve niche markets that stock insurers ignore.
The tension between transparency and autonomy will likely persist. If pricing gaps widen further, pressure from buyers and brokers may force mutuals to disclose more of their methodology. For now, the market remains fragmented, and the three quotes on the manufacturer's board stand as a testament to that fragmentation.
Lessons for Risk Managers and Brokers
For risk managers, this case reinforces the importance of shopping multiple mutuals for D&O coverage. A single quote may not reflect the market's true range, and the difference can be significant. The risk manager in this story saved roughly $70,000 by accepting Mutual A's quote, but only because the broker had relationships with all three carriers.
Brokers should ask each mutual for an underwriting file summary, even if the carrier resists. Mutual A provided one; the others did not. A summary reveals the factors that drove the price and helps the broker identify which mutual's philosophy aligns best with the client's risk profile. Comparing not just premium but also coverage triggers — such as the definition of "claim" and the scope of entity coverage — is essential, because a cheaper policy may have narrower terms.
Risk managers should track pricing dispersion over renewal cycles. If the gap between the lowest and highest quote narrows, it may signal market consolidation or a shift toward standardized pricing. If it widens, it may indicate that some mutuals are becoming more selective or that reinsurance costs are diverging. Either way, the trend provides useful intelligence for future placements.
The mutual sector's lack of a benchmarking tool is a gap that the industry could fill. A simple database — anonymized and aggregated — showing premium ranges for common D&O exposures would help buyers negotiate. Until then, the best defense is a well-informed broker and a willingness to ask hard questions about how each mutual arrived at its number.
This article is for informational purposes only and does not constitute professional advice. Risk managers and brokers should consult qualified professionals for guidance specific to their circumstances.