One Annual Account Rebalancing Fee Erases a Decade of Dividend Reinvestment Gains
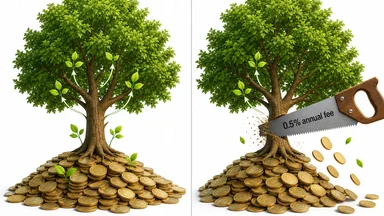
Dividend reinvestment is one of the most reliable engines of long-term portfolio growth. Yet many investors overlook a quiet adversary: the annual rebalancing fee. A charge as small as 0.5% of assets, applied each year, can erase more than half the gains from a decade of reinvested dividends. This article dissects how that happens—through fee structures, tax code interactions, and brokerage contract terms—and offers a path to avoid the drain.
The Hidden Fee That Silently Drains Your Portfolio
Annual rebalancing fees typically range from 0.5% to 1% of assets under management. Unlike visible trading commissions, these fees are deducted automatically, often from cash balances or by selling small amounts of holdings. Over time, the effect compounds just as returns do—but in the wrong direction.
Brokerage disclosures bury these charges in fine print. A Schwab or Fidelity account agreement might mention an “annual advisory fee” in a dense paragraph, while robo-advisors like Betterment or Wealthfront advertise low management fees but add rebalancing costs that vary by portfolio complexity. A $100,000 portfolio paying a 0.5% fee loses $500 each year, whether markets rise or fall.
The invisibility is the problem. Investors track trading commissions and expense ratios but rarely notice the annual deduction. Over a decade, $500 per year at a 7% opportunity cost becomes roughly $7,000 in foregone growth—enough to erase years of dividend reinvestment gains. The fee does not just cost money; it costs compounding time.
Some brokers justify the fee as compensation for automated rebalancing, tax-loss harvesting, and portfolio optimization. But the value of those services varies widely. An investor with a simple three-fund portfolio may pay for rebalancing that takes 15 minutes per quarter, while a complex portfolio with dozens of holdings might benefit from professional oversight. The key is knowing what you are paying for.
How Dividend Reinvestment Gains Actually Build Over a Decade
Dividend reinvestment works by using cash dividends to purchase additional shares of the same stock or fund. Each quarter, the new shares themselves begin earning dividends, creating a compounding cycle. Over ten years, a 3% dividend yield reinvested without friction can nearly double the effective yield on the original investment, assuming no price change.
Consider a $10,000 investment in a dividend-paying ETF with a 3% yield and 8% annual total return (price appreciation plus dividends). In year one, dividends add $300, buying roughly 30 additional shares at $10 each. By year ten, the portfolio holds more than 200 shares, and annual dividends exceed $600—effectively a 6% yield on the original principal.
The gains hinge on low-cost accumulation. Every dollar paid in fees or taxes reduces the number of new shares purchased, breaking the compounding chain. A 0.5% annual fee on the growing portfolio consumes a larger dollar amount each year, accelerating the drag. The difference between a portfolio growing at 7.5% (after fee) versus 8% (no fee) may seem small, but over ten years it compounds to a meaningful gap.
Market timing is irrelevant here. The strategy works because it is automatic: dividends arrive, shares are bought, and the cycle repeats. Any interruption—a fee deducted from cash, a taxable sale triggered by rebalancing—disrupts the rhythm. The investor who minimizes friction keeps more of the compounding benefit.
The Tax Code's Role in Amplifying or Eroding Returns
The Internal Revenue Code treats rebalancing as a sale, making it a taxable event. When a portfolio is rebalanced—selling appreciated assets to buy underweighted ones—capital gains taxes are triggered. For dividend-paying stocks held long-term, those gains are taxed at preferential rates (0%, 15%, or 20% depending on taxable income), but the tax bill still reduces the amount available for reinvestment.
Qualified dividends themselves are taxed at the same preferential rates. An investor in the 22% ordinary income bracket pays 15% on qualified dividends and long-term capital gains. If rebalancing forces the sale of shares held less than a year, the gain is taxed as ordinary income—potentially at a much higher rate. The tax code thus penalizes frequent rebalancing in taxable accounts.
Wash-sale rules add another layer. When an investor sells a dividend stock at a loss to harvest the tax benefit, the IRS prohibits repurchasing a substantially identical security within 30 days. This limits the ability to rebalance while harvesting losses. For dividend-focused portfolios, the rule can trap investors: they cannot sell a losing position to rebalance without waiting a month, during which dividends may be paid and the market may move.
The interaction between rebalancing fees and taxes is particularly pernicious. A fee reduces the portfolio value, but the IRS does not allow a deduction for the fee in a taxable account (unless it exceeds 2% of adjusted gross income, a high bar). The investor pays the fee with after-tax dollars, then pays tax on gains that are partly artificial—a double hit that erodes real returns.
Contractual Traps in Brokerage Account Agreements
Brokerage account agreements contain terms that can surprise investors. Many firms charge a per-rebalance fee or a per-trade commission that applies even to automated rebalancing. For example, a broker might offer free trades but charge $10 per rebalance trade, and if the portfolio rebalances quarterly, that adds $40 per year—small but additive.
Custodial fees for retirement accounts are another hidden cost. IRAs and 401(k)s often have annual custodial fees ranging from $25 to $100, plus per-transaction fees for certain investments. These fees are deducted from the account, reducing the balance that compounds. In a decade, a $50 annual custodial fee at 7% growth becomes roughly $700 in lost value.
Fine print may allow fee changes with as little as 30 days' notice. An investor who signs up for a low-cost brokerage may later find that rebalancing fees have been introduced or increased. The contract typically grants the broker unilateral power to modify fees, leaving the investor with a choice: accept the new fees or move assets to another firm, which itself may trigger exit fees or taxable events.
Expats face additional complexity. Non-U.S. residents may be subject to withholding taxes on dividends (often 15% or 30%) and may incur reporting costs for foreign accounts. Some brokers charge extra for maintaining accounts for expats, and rebalancing across multiple currencies can introduce forex costs. The combination of fees, withholding, and reporting can turn a modest dividend portfolio into a compliance burden.
Real-World Case: A Decade of Compounding vs. One Fee
Let us walk through a concrete example. Assume an initial investment of $10,000 in a diversified equity portfolio yielding 3% in dividends, with an 8% annual total return (5% price appreciation plus 3% dividends). Dividends are reinvested quarterly, and the portfolio is rebalanced annually to maintain target allocations. Two scenarios: one with no rebalancing fee, another with a 0.5% annual fee deducted from the account.
Without the fee, the portfolio grows to approximately $21,589 after ten years. The dividends reinvested over that period total roughly $4,800, contributing about $2,400 in growth from compounding. The final value reflects the full benefit of reinvestment.
With a 0.5% annual fee, the portfolio grows to approximately $20,527. The fee has consumed $1,062—more than one-fifth of the total dividend reinvestment gains. In fact, the fee erases over half the gains attributable to dividend compounding (the difference between the no-fee and fee scenarios is $1,062, while the dividend growth portion is roughly $2,400). The investor ends up with a significantly smaller nest egg, all because of a seemingly small annual charge.
The numbers are illustrative, not precise, because actual returns vary. But the principle holds: a recurring fee that scales with assets compounds against the investor. The longer the time horizon, the greater the damage. An investor saving for retirement over 30 years might lose tens of thousands of dollars to a 0.5% fee that could have been avoided.
Trade-Offs and Counter-Arguments: When a Fee Might Be Worth It
Not all rebalancing fees are pure waste. For investors who lack the time or discipline to rebalance manually, an automated service can enforce good habits. A 0.5% fee that prevents emotional trading during a market downturn might justify itself. Similarly, a portfolio with complex holdings—multiple asset classes, tax-sensitive strategies, or international exposure—may benefit from professional rebalancing that a flat fee covers.
Consider a retiree who holds a mix of stocks, bonds, real estate investment trusts, and commodities. Rebalancing manually would require monitoring correlations, tax implications, and withdrawal sequencing. A robo-advisor or human advisor charging a modest fee might deliver better after-tax returns than a DIY approach that triggers costly mistakes. The key is to calculate the net benefit: if the fee is 0.5% but the advisor's tax-loss harvesting saves 0.3% annually, the effective cost drops to 0.2%.
Another counter-argument: some brokers offer rebalancing as part of a flat management fee that also includes financial planning, estate planning, and tax advice. For a client who uses all those services, the rebalancing component may be a small fraction of the total cost. The problem arises when investors pay for services they do not use. A young accumulator with a simple portfolio should not subsidize planning services they do not need.
The trade-off also depends on account type. In a tax-advantaged retirement account, rebalancing triggers no immediate tax, so the fee is the primary concern. In a taxable account, the tax cost of rebalancing can dwarf the fee itself. An investor who rebalances annually in a taxable account might incur capital gains taxes of 15% on appreciated positions, which could amount to far more than a 0.5% fee. In that case, the fee is the smaller problem; the real drain is the tax event. Strategies like directing new contributions to underweighted asset classes can reduce the need to sell, thereby avoiding both the fee and the tax.
How to Structure a Portfolio That Avoids This Drain
The simplest fix is to use ETFs that rebalance internally at no cost to the holder. A total stock market ETF, for example, automatically adjusts its holdings as companies enter and leave the index. The investor never pays a rebalancing fee because the ETF does the work. Similarly, a target-date fund rebalances according to its glide path, and the cost is built into the expense ratio—typically lower than separate advisory fees.
Set automatic dividend reinvestment through your brokerage, and confirm that the reinvestment is free of commissions. Many brokers offer DRIP (Dividend Reinvestment Plan) without charge, but some charge a small fee per reinvestment. That fee, if present, should be disclosed in the account agreement. If it exists, consider switching to a broker that offers free DRIP.
Choose a broker with a flat fee structure or no rebalancing costs. Some discount brokers, like Vanguard or Fidelity, offer low-cost index funds and do not charge for rebalancing trades. Robo-advisors may charge a management fee that includes rebalancing, but compare the total cost to a DIY approach. For a simple portfolio, the DIY route often wins.
Tax-loss harvest only when the net benefit exceeds the transaction cost. Harvesting a $3,000 loss might save $660 in taxes (at 22% bracket), but if the trade triggers a $10 commission and a $50 rebalancing fee, the benefit shrinks. For small portfolios, the costs can outweigh the savings. Focus on long-term holdings and avoid unnecessary trading.
Three Questions to Ask Before Signing Any Brokerage Agreement
Before opening any brokerage account, ask three questions. First: Is there a periodic rebalancing fee? Request a dollar estimate for your expected portfolio size and trading frequency. If the answer is vague, ask for it in writing. A broker that cannot quantify the fee likely has hidden costs.
Second: Are dividend reinvestments free, or subject to commission? Some brokers charge a flat fee per DRIP transaction, which can add up over decades. A $2 commission per reinvestment on a portfolio with 20 dividend-paying stocks, each paying quarterly, amounts to $160 per year—a significant drag.
Third: What triggers a taxable event in the account structure? Understand whether rebalancing, dividend reinvestment, or account transfers create capital gains or ordinary income. For taxable accounts, the goal is to minimize taxable events. For retirement accounts, the concern is fees, not taxes, but the same principle applies: avoid unnecessary costs.
These questions are not exhaustive, but they cover the most common traps. A broker that cannot answer them clearly may not have your best interests in mind. Remember, the account agreement is a contract; read it before signing, and if the fees are buried, consider that a red flag.
Conclusion: The Fee That Keeps on Taking
Annual rebalancing fees are not inevitable. With careful planning—choosing the right broker, using low-cost ETFs, automating reinvestment, and understanding tax consequences—investors can avoid the silent drain that erodes a decade of dividend reinvestment gains. The compounding that builds wealth can also destroy it when fees compound in the opposite direction. By staying informed and asking the right questions, you keep more of what you earn.
This article provides general informational analysis and does not constitute personalized tax, legal, or investment advice. Consult a qualified professional for your specific situation.