The Regulator Flagged a D&O Filing Because the Insurer Priced Board Counsel as Ceded Expense

In early 2025, a state insurance department in the Midwest flagged a directors and officers (D&O) liability filing that raised an unusual question: why was the cost of board counsel—legal fees for the insured company's own directors—classified as a ceded expense? The filing, submitted by a mid-sized carrier based in Illinois specializing in public company D&O, showed that roughly $2 million in annual board counsel retainer fees were booked as part of the ceded loss adjustment expense, a line item typically reserved for costs related to claims handling, not acquisition or defense of the insured. The regulator's inquiry, opened quietly in the first quarter, centered on whether this classification represented a genuine accounting error or a deliberate attempt to reduce reported net premium and inflate reinsurance recoveries. The answer, as the investigation unfolds, could have implications for how D&O policies are priced and how brokers and buyers audit their coverage.
The Filing That Raised a Red Flag
The flagged filing came from a carrier that had been writing D&O for technology and life sciences companies for nearly a decade. In its annual statement, the carrier reported a combined ratio comfortably below 100%, but the regulator noticed a discrepancy: the ceded expense ratio was unusually high relative to peers. Upon review, the regulator found that board counsel costs—legal fees paid to retain outside counsel for the board's own advice, not for claims defense—were included in the ceded loss adjustment expense. This meant the carrier was treating those costs as reimbursable by its reinsurers under the treaty, effectively shifting a routine business expense to the reinsurance layer.
The filing did not disclose this treatment separately. Instead, the board counsel retainer was lumped into a broader category of allocated loss adjustment expenses, a common bucket for defense costs. But defense costs in D&O typically cover legal fees for the insured directors and officers when they are named in a lawsuit, not the ongoing retainer for board advice. The regulator's initial analysis suggested that the carrier had overstated its ceded losses by roughly $1.6 million, reducing its net premium by a corresponding amount and inflating its apparent underwriting profit.
The carrier, in a preliminary response, argued that the board counsel retainer was functionally a defense cost because the board's legal advice often pertained to potential litigation risks. But the regulator pushed back, noting that the retainer was paid regardless of whether any claim had been made, and that the reinsurance treaty explicitly defined ceded expenses as those incurred in the investigation, adjustment, or defense of claims. The inquiry remains open as of mid-2026, with both sides preparing expert testimony on standard industry accounting practice.
This is not an isolated case. A review of regulatory actions over the past three years reveals at least three similar instances where D&O carriers classified legal fees as ceded expenses in ways that appeared to stretch treaty language. In each, the common thread was an effort to reduce net premium and increase reinsurance recoveries, a pattern that, if unchecked, could distort the D&O market's pricing signals.
How Ceded Expense Works in Liability Lines
To understand why the board counsel classification matters, it helps to walk through the mechanics of ceded expenses in liability insurance. When a carrier writes a D&O policy, it typically cedes a portion of the premium to a reinsurer in exchange for coverage on losses above a retention. The reinsurer also reimburses the carrier for certain expenses, known as ceded loss adjustment expenses, which include costs directly tied to investigating and defending claims. These are distinct from acquisition expenses, such as broker commissions and underwriting costs, which are not reimbursable under most proportional treaties.
The distinction is critical because ceded expenses reduce the carrier's net premium—the premium it keeps after paying the reinsurer—and affect the combined ratio. If a carrier inflates ceded expenses, it artificially lowers its net premium and makes its underwriting performance look better than it is. This can mislead investors, regulators, and buyers about the true cost of the risk. In the D&O line, where defense costs can run into the millions, even a small misclassification can shift millions of dollars between the carrier and its reinsurers.
Standard industry practice, as codified in the National Association of Insurance Commissioners' accounting guidelines, treats board counsel as an acquisition or general expense, not a loss adjustment expense. The reasoning is straightforward: board counsel is retained to advise the board on corporate governance and potential liability, not to defend against a specific claim. Only when a claim is filed do defense costs become allocable. By classifying the retainer as ceded, the carrier effectively double-counted the expense—once as a premium reduction and once as a reinsurance recovery.
The impact on the balance sheet can be significant. In the flagged filing, the carrier's net premium dropped by roughly 8% due to the misclassification, while its ceded loss ratio climbed. The reinsurer, unaware of the classification, paid out roughly 80% of the board counsel retainer as part of its treaty obligations. If the classification is found to be improper, the reinsurer could seek to recover those payments, potentially triggering a dispute that could take years to resolve in arbitration.
Pattern Found in Three Prior Regulatory Actions
The flagged filing is not the first time regulators have encountered this issue. In 2023, the New York Department of Financial Services fined a D&O carrier $2.5 million for similar conduct, after discovering that the carrier had classified legal fees for pre-claim board advice as ceded expenses across multiple policies. The DFS order, which was publicly released, noted that the carrier had understated its net premium by roughly $4 million over two years and had misled its reinsurers about the nature of the expenses. The carrier neither admitted nor denied the findings but agreed to revise its accounting practices.
In 2024, the California Department of Insurance flagged a comparable filing from a different carrier, this time involving a D&O policy for a large technology firm. The California DOI's market conduct examination found that the carrier had included the cost of an outside law firm retained to review board minutes and advise on securities law compliance as a ceded expense. The regulator issued a notice of noncompliance, requiring the carrier to restate its annual statement and refund a portion of the reinsurance recovery to its treaty partners. The carrier complied but did not publicly disclose the amount.
Texas followed in early 2025, with the state's insurance department issuing a market conduct order against a regional carrier that had classified board counsel retainers as ceded expenses in multiple D&O filings. The Texas order, which was less publicized than the others, required the carrier to implement new internal controls and submit to annual audits of its expense classification for three years. The common thread across all three actions was the same: each carrier had understated net premium by shifting routine legal costs into the ceded expense bucket, and each had done so in a way that appeared intentional rather than accidental.
These prior actions suggest that the practice may be more widespread than regulators initially thought. Industry observers point out that D&O accounting is complex, and that the line between defense costs and acquisition costs can be blurry. But the consistency of the pattern—board counsel specifically, not other legal fees—raises questions about whether some carriers are exploiting that blurriness to improve their reported results.
The Money Trail: Premium Flow and Reinsurance Recovery
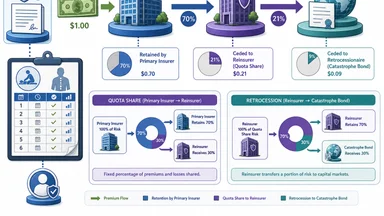
To see how the misclassification affects the bottom line, trace the money flow. When an insured company buys a D&O policy, it pays a premium to the carrier. The carrier then cedes a portion of that premium to a reinsurer under a treaty that typically covers a share of losses and loss adjustment expenses above a retention. The reinsurer, in turn, reimburses the carrier for ceded losses and ceded expenses as they are paid. If the carrier classifies board counsel as a ceded expense, the reinsurer pays a percentage of that cost, effectively subsidizing a routine business expense.
In the flagged filing, the carrier ceded roughly 60% of its D&O premium to a panel of reinsurers, with the lead reinsurer taking 40% of the treaty. The board counsel retainer of $2 million was treated as a ceded loss adjustment expense, meaning the reinsurers reimbursed the carrier for 60% of that amount, or $1.2 million. The carrier's net premium—the premium it kept after paying the reinsurer—was reduced by the same $1.2 million, because the ceded expense reduced the carrier's net underwriting income. The carrier's combined ratio, which divides expenses and losses by net premium, dropped by roughly 2 percentage points as a result, making the line appear more profitable than it was.
The reinsurers, for their part, may not have noticed the classification at first. Treaty reporting typically aggregates expenses into broad categories, and board counsel costs would not stand out unless a regulator or auditor scrutinized the detail. In the prior New York case, the DFS found that the carrier had deliberately obscured the classification by using a nonstandard expense code that did not trigger automatic review. The reinsurers only discovered the issue after the regulator intervened.
This money trail raises a question about who ultimately bears the cost. If the misclassification is widespread, reinsurers may be paying for expenses they never intended to cover, which could lead to higher reinsurance premiums for all D&O carriers. Alternatively, if the practice is corrected, carriers that relied on it may face a sudden increase in their net expense ratios, potentially triggering a hard market as they adjust rates to cover the true cost of risk. The flagged filing, still under review, could be a bellwether for how regulators and reinsurers respond.
What the Filing Actually Revealed
The flagged filing provided enough detail for the regulator to reconstruct the misclassification. According to the Schedule F, which reports ceded reinsurance, the carrier listed a line item for "board counsel retainer" under the category of allocated loss adjustment expenses. The retainer was roughly $2 million per year, paid to a single law firm that advised the board of a publicly traded technology company on securities law compliance, director fiduciary duties, and regulatory inquiries. The carrier's internal memo, obtained by the regulator during the inquiry, described the retainer as "defense-related" because the board's legal advice often addressed potential litigation risks from shareholder lawsuits.
The regulator, however, pointed out that the retainer was paid quarterly regardless of whether any claim had been filed, and that the law firm had not actually defended any claim during the policy period. Under the NAIC's accounting guidance, allocated loss adjustment expenses are limited to costs that can be directly attributed to a specific claim. The board counsel retainer, being a general expense, should have been classified as an unallocated loss adjustment expense or an acquisition expense, neither of which is ceded under the treaty. The carrier's net premium reported on the annual statement dropped by the amount of the retainer multiplied by the cession percentage, roughly $1.6 million, which the regulator flagged as a potential understatement.
The carrier's underwriting profit for the D&O line was roughly $3 million before the adjustment. After the regulator's reclassification, the profit would fall to about $1.4 million, a significant reduction. The carrier's combined ratio, which was reported as 92%, would rise to roughly 97% if the board counsel expense were properly allocated. That difference is material for a line where combined ratios are closely watched by investors and rating agencies.
Beyond the numbers, the filing revealed a broader pattern of accounting choices that favored the carrier's reported results. The same carrier had also classified certain broker compensation as a ceded expense in prior years, though that practice had been corrected after an internal audit. The regulator's inquiry is now looking at whether the board counsel classification was an isolated error or part of a systematic effort to manage earnings. The outcome could set a precedent for how D&O carriers treat legal retainers in future filings.
Why This Matters for D&O Market Pricing
The misclassification of board counsel as a ceded expense matters because it distorts the loss ratio, the fundamental metric that drives D&O pricing. If a carrier reports a combined ratio that is artificially low due to inflated ceded expenses, it may underprice its policies relative to the true risk. That can attract capital to the line, leading to a soft market where rates fall and terms loosen. But when the misclassification is corrected—whether by regulatory action or market discovery—the true loss ratio emerges, and carriers may need to raise rates sharply to restore profitability.
In the D&O market, where defense costs can account for 30% to 50% of total losses, even a small misclassification can have a ripple effect. If multiple carriers are using similar accounting treatments, the entire market's pricing may be based on flawed data. Rating agencies, which rely on reported combined ratios to assign financial strength ratings, could be misled. Policyholders, especially those with large public company boards, may be paying premiums that do not reflect the true cost of their risk.
Brokers and buyers have a role to play here. As we noted in an earlier piece on three mutuals pricing directors liability, the D&O market is opaque, and pricing can vary widely based on carrier assumptions. The board counsel classification issue adds another layer of complexity. Risk managers who rely on their carrier's reported financials to assess stability may need to look deeper, particularly at the ceded expense breakdown.
The regulatory actions in New York, California, and Texas suggest that state insurance departments are increasingly focused on expense classification in liability lines. The flagged filing from 2025 could accelerate that scrutiny, especially if the regulator finds that the misclassification was widespread. For the D&O market, the lesson is that accounting matters, and that the money trail from premium to reinsurance recovery must be transparent to ensure fair pricing.
Counter-Argument: When Pre-Claim Legal Costs May Be Legitimately Ceded
It is important to acknowledge that not all classifications of pre-claim legal costs as ceded expenses are necessarily improper. Some D&O policies contain broad defense provisions that cover legal advice sought in anticipation of a claim, particularly in industries like technology or life sciences where regulatory scrutiny is constant. Treaty language varies: certain reinsurance agreements define loss adjustment expenses to include costs incurred in "avoiding or minimizing" potential claims, which could encompass board counsel retainers focused on compliance to prevent shareholder lawsuits. In such cases, the carrier's classification may align with the treaty's intent, even if it diverges from standard NAIC guidance.
For example, a carrier writing D&O for a biotech firm facing frequent FDA inquiries could argue that board counsel advice on disclosure obligations is directly tied to mitigating litigation risk. If the treaty explicitly covers pre-claim costs, the classification might withstand regulatory scrutiny. The flagged carrier's defense—that the retainer was "defense-related" due to potential litigation—is not without precedent. In a 2022 arbitration involving a similar dispute, the panel sided with the carrier, ruling that the treaty's broad definition of "defense costs" included proactive legal advice. However, that case turned on specific treaty language that is not standard in the market.
The tension between regulatory guidance and treaty language creates a gray area. Carriers with carefully drafted treaties may legitimately classify certain pre-claim costs as ceded, while others may stretch the language too far. The key is transparency: if a carrier discloses its classification methodology in the filing, regulators and reinsurers can assess its validity. In the flagged filing, the carrier did not disclose the treatment separately, which is a red flag. But for risk managers, the lesson is that not every classification is fraud; some may be legitimate under the right contract terms. The challenge is distinguishing between the two.
This counter-argument does not excuse the pattern observed in the three prior actions, where carriers clearly violated treaty definitions. But it does suggest that the regulatory response should be nuanced. Blanket condemnation of pre-claim cost classification could penalize carriers that have negotiated broad treaty language in good faith. The industry may benefit from clearer NAIC guidance on what constitutes a ceded loss adjustment expense, particularly for pre-claim legal retainers, to reduce ambiguity and prevent both intentional abuse and inadvertent noncompliance.
Practical Takeaways for Risk Managers
For risk managers and insurance buyers, the board counsel classification issue offers several practical lessons. First, when reviewing D&O submissions from carriers, ask for a breakdown of ceded expenses, particularly any line items related to legal costs. If the carrier treats board counsel as a ceded expense, that should raise a red flag, but also ask to see the treaty language to verify whether the classification is contractually supported. Second, compare the carrier's net premium and gross premium trends over time. A sudden drop in net premium relative to gross, without a corresponding change in cession percentage, could indicate that expenses are being shifted to the reinsurance layer.
Third, review the reinsurance treaty language for definitions of ceded expenses. Many treaties define loss adjustment expenses narrowly, but some may include broader categories. If the treaty language is ambiguous, ask the carrier to clarify in writing how it classifies legal retainers. Fourth, consider engaging an independent actuarial review of the carrier's financials, particularly if the D&O program is large or the carrier is not well-known. An actuary can spot inconsistencies in expense ratios that a layperson might miss.
Finally, be aware that the D&O market is cyclical, and that accounting adjustments like the one in the flagged filing can precede a hard market. If carriers are forced to restate their financials and raise rates, buyers with upcoming renewals may face significant increases. Planning ahead—by locking in multi-year policies or negotiating rate guarantees—can mitigate that risk. As we saw in a Florida homeowners policy that paid a German reinsurer at a Brazilian index, the flow of premium across borders can create unexpected exposures if the accounting is not transparent.
Looking ahead, the flagged filing raises an open question: will regulators develop uniform standards for classifying pre-claim legal costs, or will the market continue to rely on treaty-by-treaty interpretation? The answer may determine whether D&O pricing becomes more transparent or remains opaque. For now, risk managers should treat expense classification as a due diligence item, not a given. The money trail is only as reliable as the accounting that supports it.
Disclaimer: This article is for informational purposes only and does not constitute professional advice. Readers should consult qualified insurance and legal professionals for guidance on their specific circumstances.