A Single Bakery’s Workers Comp Audit Found a Faulty Payroll Split Between Icing and Delivery
The bakery on Elm Street had been making pastries for a decade. Its workers compensation policy, bundled into a business owner's policy (BOP), cost roughly $8,000 a year on a $200,000 payroll. The owner thought the coverage was straightforward: bakers mix icing, drivers deliver cakes, and the insurer priced the risk accordingly. Then came the audit.
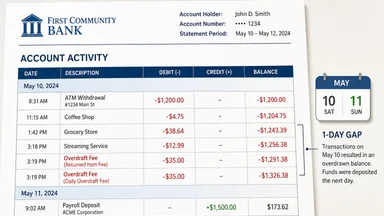
In early 2025, the carrier's premium auditor flagged a discrepancy. The bakery had classified 20% of its payroll as delivery — the same split used for the past three renewals. But the auditor recalculated based on actual hours and found that delivery drivers accounted for 40% of payroll. The result: a $14,000 back-premium bill covering two years of underpaid premiums, plus interest.
The bakery owner was stunned. No delivery driver had filed a claim in half a decade. The only reported injury was a $2,300 slip on icing residue in the kitchen. Yet the carrier insisted the reclassification was correct under National Council on Compensation Insurance (NCCI) class codes. The story illustrates a growing tension in small-business insurance: the gap between how risk is priced and how it actually behaves.
The Icing vs. Delivery Split That Triggered a $14,000 Audit
The audit began with a routine payroll verification. The carrier's auditor requested time records, payroll summaries, and job descriptions. The bakery's owner had assumed that drivers who spent most of their shift in the store — helping with icing between deliveries — could be classified under the lower-risk baking code (class code 2501, bakery employees). The auditor disagreed, reclassifying all driver hours under code 7219, trucking/delivery, which carries rates roughly three times higher.
The $14,000 figure came from applying the higher rate to the reclassified payroll for the two prior policy periods. The bakery had paid $8,000 annually based on a 20% delivery split. The auditor calculated that the correct premium should have been $11,200 per year — a $3,200 annual shortfall, plus a late-payment penalty and audit fee. The owner had no recourse: the policy's audit provision allowed the carrier to recalculate premium based on actual exposure, and the statute of limitations for contesting audits in that state is typically 12 months from the audit date.
NAIC complaint data for 2024 shows a rising number of disputes over payroll classification in small BOPs. The most common grievances: carriers reclassifying clerical or sales staff into higher-risk codes after the fact, or auditors applying class codes inconsistently across similar businesses. The bakery's case fits a pattern where mixed-occupation payrolls — especially those involving delivery — are a frequent source of post-issuance premium adjustments.
How Class Codes and Payroll Allocation Feed Premium Flow
Workers compensation rates vary dramatically by class code. For a bakery, code 2501 (bakery, including retail sales) carries a rate of roughly $2.50 per $100 of payroll in many states. Code 7219 (trucking/delivery) runs closer to $7.50 per $100. That three-to-one ratio means a small shift in payroll allocation can double or triple the premium. The carrier's underwriting algorithm relies on the split to set the base premium; it does not adjust for the bakery's actual loss history until the experience modification factor is applied — often a year or more later.
The premium flow works like this: the bakery pays $8,000. The carrier retains a portion for expenses and claims, then cedes a quota share — typically 50% for small workers comp — to a reinsurer. The reinsurer receives $4,000 of the original premium. If the audit adds $3,200 in back premium, the carrier cedes another $1,600 to the reinsurer. For the reinsurer, this is almost pure profit: the additional premium comes without a corresponding increase in expected losses, because the underlying risk (the drivers) was already covered. The reinsurer simply collects a higher share of a pool that was underpriced.
AM Best's 2025 report on the U.S. property and casualty industry noted that underwriting profits reached their highest level in a decade, partly driven by audit recoveries and premium adjustments on existing policies. The bakery's $14,000 audit contributed to that industry-wide gain. But for the individual business, the recovery feels less like fine-tuning and more like a penalty for a classification error the owner didn't know existed.
The Bakery's Actual Loss History Told a Different Story
The bakery's loss experience over five years was nearly spotless. The only claim was a kitchen slip that cost $2,300 in medical payments and lost time. That loss, under the baking class code, would have produced a low experience modification factor — roughly 0.85, meaning a 15% discount off the manual premium. But because the carrier applied the delivery code to 40% of payroll, the experience mod was calculated against a higher base. The mod itself remained low, but the base was inflated, so the final premium was still higher than if the split had been correct from the start.
This is a subtle but important point. The experience modification system is designed to reward good loss history. But it only works when the payroll allocation accurately reflects the risk. If a bakery with safe drivers is misclassified as a high-delivery operation, the mod discount is applied to an artificially large base. The bakery ends up paying more despite having no delivery claims. The system penalizes the classification error, not the actual risk.
Some insurers argue that class codes are a necessary simplification. They cannot underwrite each employee individually, so they rely on broad categories that reflect industry-wide loss costs. But for a small business with a handful of employees, the difference between a 20% and 40% delivery split can be the difference between a profitable policy and a loss leader. The bakery's case shows that the class-code system, while efficient for carriers, can create inequities for businesses whose risk profile doesn't match the average.
Premium Flow: From Bakery to Reinsurer and Back
To understand why the carrier pursued the audit so aggressively, follow the money. The original $8,000 premium was split: roughly $2,000 went to agent commission and overhead, $3,000 set aside for expected losses and loss adjustment expenses, and $3,000 ceded to a reinsurer under a 50% quota share treaty. The reinsurer, in turn, paid a ceding commission of about 20% back to the carrier, netting the carrier an extra $600. The carrier's underwriting profit on the policy was thin — maybe $500 after all costs.
The audit added $3,200 in premium. Of that, $1,600 went to the reinsurer. The carrier kept $1,600, minus a small audit expense. That $1,600 nearly tripled the carrier's profit on the policy. For the reinsurer, the additional $1,600 was almost pure margin: the treaty already covered the delivery risk, and no new loss reserves were needed. The reinsurer's combined ratio on the ceded business improved accordingly.
This dynamic explains why carriers invest in premium audits. According to a 2024 survey by the Insurance Research Council, roughly 12% of small workers comp policies generate additional premium through audits. The average adjustment is about $2,500. For a carrier writing 100,000 such policies, that translates to $30 million in unexpected revenue — much of it flowing to reinsurers as well. The bakery's audit was not an anomaly; it was a predictable outcome of a system designed to capture misallocated payroll.
Why the Bakery's Broker Missed the Split at Renewal
The bakery's broker had handled the account for years. At each renewal, the broker requested the same classification from the prior carrier's system, assuming it was correct. No site visit was conducted. No breakdown of job duties was requested. The standard BOP application has a single line for workers compensation payroll, with a checkbox for the class code. The broker checked "bakery" and moved on.
The broker's commission — typically 10% to 15% of premium — was linked to the policy's size. A higher premium meant a higher commission, but the broker had no incentive to increase the premium through reclassification. The oversight was not malicious; it was a product of routine. The broker relied on the carrier's underwriting system to flag errors. But the system only flags errors when the payroll split deviates from industry averages, not when it is simply wrong.
Some brokers now use payroll-audit checklists at renewal, asking clients to confirm hours by job function. But many small-business brokers resist this, arguing that it adds friction to the renewal process and may drive clients to competitors who offer a simpler experience. The bakery's case suggests that the friction of a five-minute payroll review is trivial compared to the cost of a $14,000 audit. Yet the industry's standard practice remains reactive: let the carrier audit after the fact, rather than verify at binding.
Real-World Variations: Similar Cases Across Industries
The bakery's dilemma is not unique. Consider a landscaping company that classifies all workers under a single code for grounds maintenance. In reality, some employees operate heavy equipment — a higher-risk classification. An audit may reallocate a portion of payroll to a code for power-driven equipment, doubling the premium for those hours. The business owner, like the baker, may have no claims from equipment operators, but the class code rate reflects industry-wide loss data, not the company's own experience.
Another example: a small restaurant that delivers food. The owner might classify delivery drivers under the restaurant code (class code 9082) at a rate of around $3.00 per $100 of payroll. An auditor could reclassify them under code 7219 at $7.50 per $100, arguing that delivery is the primary job function. The restaurant's payroll split might shift from 10% delivery to 25%, triggering a significant back-premium. The owner may protest that drivers also help in the kitchen, but the auditor's interpretation often prevails.
These cases share a common thread: the business owner's actual risk profile — low claims, safe operations — is invisible to the class-code system. The system uses broad averages, not individual loss data, to set rates. Only after a loss experience modification factor is calculated (which can take a year or more) does the individual risk profile influence the premium. By then, the audit has already locked in a higher base.
Trade-Offs: Class Code Simplicity vs. Individual Fairness
Class codes offer efficiency. Without them, carriers would need to underwrite each employee's specific duties, a process that would slow policy issuance and increase costs. For most businesses, the broad categories work well enough. But for businesses with mixed job types — where employees split time between low-risk and higher-risk tasks — the system creates friction.
One alternative is a loss-sensitive rating plan, where the premium adjusts based on actual claims rather than payroll allocation. For example, a bakery with a clean loss history could opt for a deductible workers comp policy, paying a lower base premium but covering the first few thousand dollars of each claim. However, these plans require accurate payroll data to set the initial premium. If the payroll split is wrong, the base premium is wrong, and the loss-sensitive adjustment may not correct it.
Another trade-off is the use of separate policies. The bakery could have purchased a stand-alone commercial auto policy for its delivery vehicles, which might have a lower rate than the trucking workers comp class code. But commercial auto does not cover workers comp for the driver; it covers liability for accidents. The driver's comp coverage would still need to be classified correctly. Splitting policies can also create gaps if coverage is not coordinated.
Some brokers advocate for a "payroll audit" at the time of binding, rather than after the fact. This means the broker or carrier reviews time records and job descriptions before the policy starts, ensuring the split is accurate from day one. The cost of this review is modest — perhaps a few hundred dollars in broker time — but it can prevent a $14,000 audit. The bakery's owner would have gladly paid $300 for a pre-binding audit to avoid the $14,000 bill.
Counter-Argument: Carriers' Perspective on Audits
Carriers defend audits as a necessary tool to ensure premium accuracy. Without audits, businesses could underreport high-risk payroll, shifting costs to other policyholders. The class-code system relies on honest reporting; audits deter manipulation. In the bakery's case, the carrier argued that the reclassification was not punitive but corrective. The delivery drivers posed a higher risk of injury — from vehicle accidents, lifting, or slips — and the premium should reflect that.
Industry data supports the higher rate for delivery drivers. According to NCCI, the loss cost for code 7219 is roughly three times that of code 2501. Delivery drivers face hazards like traffic, loading and unloading, and uneven surfaces. Even if the bakery's drivers had no claims, the pooled risk across all delivery drivers justifies the higher rate. The carrier's underwriter cannot know that this particular bakery's drivers are exceptionally safe; the class code is a proxy for average risk.
However, the bakery's owner might argue that the audit penalized a classification error that was not intentional. The owner had no reason to misclassify; the broker had set up the split years ago. The audit felt like a gotcha, not a fair adjustment. This tension between systemic accuracy and individual fairness is inherent in the class-code system. Carriers could reduce friction by offering pre-binding classification reviews, but few do, because the audit revenue itself is a profit center.
Practical Steps for Small Business Owners
First, audit your payroll split before the carrier does. Request a class-code worksheet from your broker or carrier and map each employee's hours to the correct code. If you have drivers who also work in the store, track their time separately. A simple spreadsheet can save thousands.
Second, ask your broker to provide the class code justification in writing. Many carriers will issue a classification confirmation at binding if requested. This document can be used to dispute an audit if the carrier later tries to reclassify the same duties. Without it, the auditor's interpretation is presumed correct.
Third, track actual losses by job type. If your delivery drivers have a clean record, document it. Some carriers offer alternative rating plans — such as loss-sensitive or deductible workers comp — that can lower premium for low-loss operations. But these plans require accurate payroll data to begin with. The bakery's clean loss history was invisible because the classification obscured it.
Fourth, reconsider your delivery vs. storefront risk profile annually. If you shift from in-store sales to more delivery, the change affects your workers comp and commercial auto exposure. A separate commercial auto policy for delivery vehicles may be cheaper than a reclassified workers comp premium. The bakery might have saved money by insuring its drivers under a commercial auto policy with a lower rate than the trucking class code.
Finally, know your audit rights. Most states require carriers to conduct audits within 12 months of policy expiration. If the carrier misses that window, the audit may be invalid. Some policies also allow the insured to request a desk audit (remote) rather than an on-site visit, which can reduce the chance of an auditor reclassifying based on a brief observation. The bakery's owner did not know these rights and waived them by signing the audit form without review.
The bakery's story is not unique. Similar cases appear in NAIC complaint databases and court dockets across the country. A miscalibrated roofing class code delayed a general liability claim by eight months in a separate case, showing how classification errors ripple beyond premium. The lesson is not that carriers are predatory, but that the system's incentives — for carriers, reinsurers, and brokers — do not always align with the small business's interest. The best defense is a proactive review of payroll, class codes, and loss data before the auditor arrives.
Disclaimer: This article is for informational purposes only and does not constitute professional insurance advice. Coverage needs vary by jurisdiction and individual circumstances. Consult a licensed insurance professional for guidance specific to your business.