Your 401(k)’s Annual Fee Exceeds the Total Return on Your Fee-Free Bond Fund
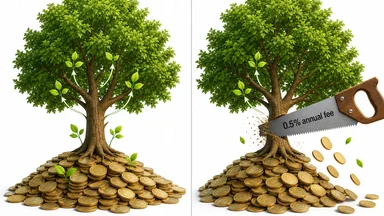
If your 401(k) earns 6% a year and charges 1% in fees, you might think the net is 5%. Over 30 years, that 1% fee consumes roughly 30% of your potential ending balance. Now consider a fee-free bond fund that yields 2–3% annually. The fee on your 401(k) alone can exceed the total return on that bond fund. This is not a hypothetical exercise. It is the arithmetic of retirement plans as they exist today.
The 1% That Gobbles 30% of Your Nest Egg
Industry data from BrightScope and the Investment Company Institute place the average all-in 401(k) fee near 1% of assets per year. That includes expense ratios on underlying funds, recordkeeping, administration, and advisory charges. For a participant with a US$50,000 balance, that is US$500 annually. Over 30 years, assuming a 6% gross return, that 1% fee reduces the final account value by about 28%—nearly a third of the money that would have been there.
To put it in starker terms: a fee-free bond fund returning 2.5% generates US$25 per US$1,000 invested each year. If your 401(k) charges a 1% fee on that same US$1,000, the fee is US$10—40% of the bond fund's return. For a participant holding a mix of stocks and bonds, the fee may still eat a disproportionate share of the fixed-income piece. The bond fund is not earning enough to cover the cost of being in the plan.
Who collects that money? Plan administrators, recordkeepers, third-party administrators, investment advisors, and the fund families themselves. In many plans, the costs are bundled into the expense ratios of the funds offered, making them nearly invisible to participants. The Department of Labor's 408(b)(2) regulation requires service providers to disclose compensation, but the disclosures are dense and often ignored.
Where the Money Goes: Recordkeeping, Administration, and Hidden Trailer Fees
Recordkeeping fees—the cost of maintaining participant accounts, processing trades, and generating statements—typically run US$20 to US$60 per participant per year. In large plans with thousands of participants, that cost is often subsidized by revenue sharing from the fund families. In small plans, the per-head cost can be US$100 or more, and participants bear it directly.
Administration costs include compliance testing, Form 5500 preparation, and fiduciary liability insurance. These are sometimes charged as a flat fee deducted from participant accounts, sometimes bundled into the expense ratio. The bundling makes it hard to compare plans. A fund with a 0.75% expense ratio may include 0.25% in revenue sharing that goes to the recordkeeper, while a similar fund with a 0.50% ratio may pass nothing back.
Trailer fees—also called 12b-1 fees in mutual funds—are ongoing commissions paid to brokers for selling certain funds. In a 401(k) context, these fees often flow to the advisor who selected the fund menu. A fund charging a 0.25% 12b-1 fee on a US$10 million plan generates US$25,000 annually for the advisor, year after year. Participants rarely see this line item; it is embedded in the fund's expense ratio.
Small plans pay more per head than giant 401(k)s. A plan with 20 participants and US$500,000 in assets might have total fees of 1.5% to 2% of assets, because fixed costs are spread over fewer people. The same fund menu in a US$1 billion plan might cost 0.5% or less. This disparity is one reason small-business owners and their employees often end up with the worst fee structures.
The Fund Menu Mirage: High-Cost Active Funds Disguised as Choices
Walk into a typical 401(k) and you will see a menu of 15 to 30 funds. Many are actively managed funds with expense ratios of 0.5% to 1.5%. Index funds, which track broad market benchmarks, cost 0.03% to 0.10% but are often absent or offered alongside higher-cost alternatives. Why would a plan fiduciary include expensive funds when cheap ones exist?
One answer is revenue sharing. Index funds typically pay no 12b-1 fees and no revenue sharing. Active funds often pay 0.25% to 0.50% in revenue to the plan's recordkeeper or advisor. That revenue offsets the plan's administrative costs, allowing the employer to offer a "free" plan—but the cost is shifted to participants through higher expense ratios. Another answer is inertia: many plans were set up years ago with a set of funds that have never been reviewed for cost efficiency. The fiduciary may lack the expertise or incentive to conduct a rigorous fee benchmarking.
A third factor is the role of financial advisors who serve as third-party administrators. These advisors may recommend funds that pay them commissions, even if cheaper alternatives exist. The Department of Labor's fiduciary rule, which would have required advisors to act in the best interest of retirement savers, was partially vacated in 2018. The current regulatory landscape under the SEC's Regulation Best Interest requires brokers to act in the customer's best interest but does not impose the same strict fiduciary duty. As a result, conflicted advice remains legal as long as the broker discloses the conflict.
Consider a concrete example: a plan with US$5 million in assets offers an actively managed large-cap growth fund with a 1.2% expense ratio and a 0.25% 12b-1 fee. An index alternative from the same asset class costs 0.05% with no 12b-1. Over 20 years, the difference in fees on a US$10,000 initial investment (assuming 7% gross return) is roughly US$4,500—nearly half the ending balance. The participant never sees that trade-off; the menu simply presents both options as equivalent choices.
The Arithmetic of Fee-Free Bond Funds: When the Fee Eats the Yield
Fee-free bond funds exist. The Vanguard Total Bond Market Index Fund, for instance, has an expense ratio of 0.05%—effectively fee-free for practical purposes. Its yield as of early 2025 is around 2.5% to 3% annually. Now place that fund inside a 401(k) that charges a 1% all-in fee. The bond fund's gross return is 2.5%; after the plan-level fee, the net return is 1.5%. But the participant also pays the fund's own expense ratio, so the net is 1.45%. The plan fee alone (1%) is 40% of the bond fund's gross yield. If the plan fee is 1.5% (common in small plans), the fee exceeds the bond fund's entire gross return, leaving a negative net return.
This is not merely an academic point. Many participants hold a significant portion of their portfolio in bonds, especially as they near retirement. A 60-year-old with US$200,000 in a target-date fund that is 40% bonds could be paying US$2,000 in total fees annually. If the bond portion returns 2.5%, that's US$2,000 in gross bond return—entirely consumed by fees. The stock portion must make up the difference, but if stocks underperform, the participant's retirement income suffers.
The problem is compounded when participants are unaware of the fee structure. A 2023 survey by the Employee Benefit Research Institute found that roughly 60% of 401(k) participants could not estimate the fees they paid. Among those who could, the median estimate was 0.5%—half the actual average. This lack of awareness means there is little market pressure on plan sponsors to reduce fees.
What You Can Do: Audit Your Plan's Fee Disclosure
Every 401(k) plan is required to provide participants with an annual fee disclosure statement under ERISA Section 404(a). This document lists the fees charged to your account, including expense ratios, administrative fees, and any transaction charges. It is not a model of clarity, but you can extract the key numbers with a systematic approach.
First, locate the fee disclosure. It is often a multi-page document mailed or emailed annually. Look for a table titled "Fee and Expense Information" or similar. Identify the total annual operating expenses for each fund you own—this is the expense ratio. Then look for a line item labeled "Plan Administrative Expenses" or "Recordkeeping Fee." This may be listed as a flat dollar amount or a percentage of assets. Add the expense ratio and the plan-level fee to get your all-in cost.
Second, compare your all-in cost to industry benchmarks. For plans with over US$100 million in assets, total fees should be under 0.5% for a typical target-date fund lineup. For plans with US$10 million to US$100 million, fees in the 0.5% to 0.8% range are reasonable. For plans under US$1 million, fees above 1.5% are common but not inevitable. You can use tools like the Department of Labor's fee disclosure comparison worksheet or BrightScope's plan ratings to benchmark your plan.
Third, if your fees are above the benchmark, consider your options. If you are still employed, you can lobby your HR department or benefits committee to add low-cost index funds or to negotiate lower recordkeeping fees. Some employers are receptive, especially if you present data showing that high fees are a fiduciary risk. If you have left the job, you can roll your 401(k) into an IRA, where you have access to funds with expense ratios as low as 0.03% and no plan-level fees. Be aware of any surrender charges or tax implications before rolling over.
Another option is to use a self-directed brokerage window within your 401(k), if your plan offers one. This allows you to invest in a broader range of securities, including low-cost ETFs, but may come with additional trading fees. Evaluate whether the potential savings outweigh the extra costs.
The Fiduciary's Role: Why Some Plans Are Better Than Others
Under ERISA, plan fiduciaries—typically the employer or a committee—are required to act solely in the interest of participants and beneficiaries, and to defray reasonable expenses of administering the plan. The Department of Labor has interpreted this to mean that fiduciaries must ensure that fees are reasonable in relation to the services provided. Yet many fiduciaries fail to conduct regular fee benchmarking. A 2024 study by the Plan Sponsor Council of America found that only about half of plan sponsors had conducted a fee benchmarking study in the past three years.
Fiduciaries who fail to monitor fees can be held personally liable for losses resulting from imprudent decisions. In the 2023 case Smith v. CommonSpirit Health, a federal court allowed a class-action lawsuit to proceed against a large hospital system for allegedly offering excessively expensive funds in its 401(k) plan. The plaintiffs argued that the plan's fees were more than double those of comparable plans. The case is ongoing, but it signals a trend: participants are increasingly willing to sue over fee issues.
For employers, the takeaway is clear: regular fee benchmarking is not just good practice; it is a fiduciary duty. Engaging an independent consultant to review the plan's fee structure every two to three years can protect both the employer and the participants. Some providers offer fee benchmarking as part of their service, but it is wise to seek an independent review to avoid conflicts of interest.
Counterargument: Low Fees Aren't Everything
Not everyone agrees that minimizing fees is the paramount goal. Some argue that active management can generate excess returns that justify higher costs. A 2022 study by S&P Dow Jones Indices found that over a 15-year period, about 60% of large-cap active managers underperformed their benchmark after fees. But that means 40% outperformed—at least before fees. After fees, the number drops further. The data does not support the idea that the average active manager adds value net of fees, but it does suggest that a minority of managers can.
Another argument is that fees are only one component of a successful retirement plan. Auto-enrollment, auto-escalation, and employer matching have a larger impact on outcomes than fee levels in many cases. A plan that charges 1% but has a 100% match up to 5% of salary is likely better than a plan with 0.5% fees and no match. The match is immediate, risk-free return, whereas fee savings compound over time. Still, the two are not mutually exclusive: a plan can have both a generous match and low fees.
There is also the behavioral aspect: participants who see low fees may be more likely to contribute and stay invested. A 2021 study by Vanguard found that participants in low-cost plans had higher savings rates and lower turnover. This suggests that fee transparency can have positive spillover effects on retirement readiness.
Conclusion: The Fee-Free Bond Fund as a Canary in the Coal Mine
The fee-free bond fund is a useful benchmark because its return is low enough that any fee becomes significant. If your 401(k) fee exceeds the yield on a safe bond fund, you are effectively paying to lose money on that portion of your portfolio. The solution is not to avoid bonds—they serve a critical diversification role—but to reduce fees across the board.
Start by understanding your plan's fee structure. Use the fee disclosure to calculate your all-in cost. Compare it to benchmarks. If it is high, take action: talk to your employer, consider a rollover, or advocate for better fund options. The arithmetic is unforgiving, but it is also empowering. Once you see where the money goes, you can decide whether it is worth it.
The 1% fee that eats 30% of your nest egg is not a law of nature. It is a feature of the current system, and it can be changed—one plan at a time.